
Business Loans. Without the Fuss.
Compare business loans by cost, eligibility, repayment, and speed — plain-English guides to help you choose the right lender and apply with confidence.
Business loans explained
Use these guides to compare business loan options by cost, eligibility, repayment structure, speed, and lender fit before you apply — so you walk into a funding decision already knowing the answers.
What to compare before you borrow
Total cost of borrowing
Look past the headline rate at the APR, arrangement fees, and the total amount repayable over the full term.
Repayment structure
Fixed monthly payments, a share of card takings, or a flexible facility — match it to how your revenue actually arrives.
Eligibility & trading history
Most lenders weigh time trading, turnover, and credit profile. Knowing yours up front avoids wasted applications.
Speed to funding
Some lenders pay out in 24–48 hours, others take weeks. If timing matters, prioritise lenders built for speed.
Security & guarantees
Check whether the loan is secured against assets or needs a personal guarantee before you commit.
Early repayment terms
If you might clear the balance early, confirm whether there are exit fees or interest savings.
Latest guides
The Boom in Unsecured and Non-Traditional Security Business Lending for Australian SMEs
The boom in unsecured and non-traditional security business lending for Australian SMEs is real, measurable, and accelerating. A record 47% of Australian small businesses now prefer non-bank lenders over the major banks [1], driven by faster decisions, flexible criteria, and a funding process that actually fits how businesses operate.
Business Loans for Regional and Rural Australian SMEs: Unique Funding Challenges and Solutions
Business loans for regional and rural Australian SMEs work differently from city lending — fewer local bank branches, income that swings with seasons, and industries banks consider higher risk all make approval harder. But specialist online lenders and government programs have closed much of that gap.
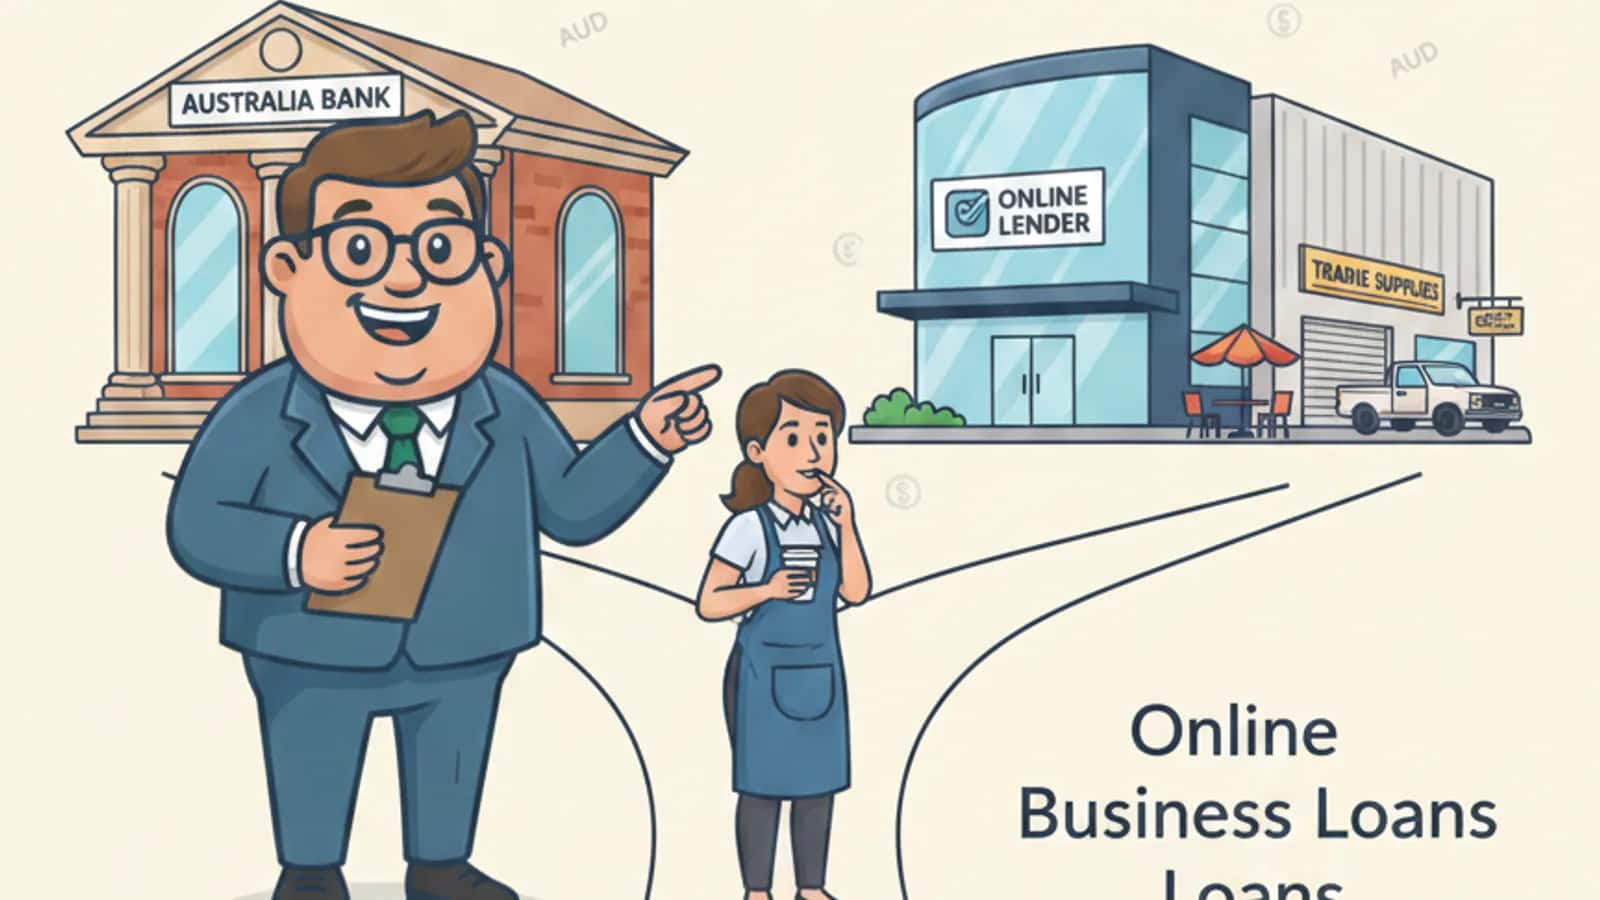
Online vs Bank Business Loans in Australia: Which Is Better for Your SME in 2026?
For most Australian SMEs that need capital quickly, online lenders win on speed, flexibility, and accessibility — especially if your credit file isn't perfect or your business is under three years old. Traditional banks still make sense for large, long-term loans where you can wait weeks and have strong financials to back you up.
Fast Business Loans Australia: Timing, Checks and Costs
Several Australian non-bank lenders can approve and fund business loans on the same day or within 24 hours, with loan amounts ranging from $5,000 to $7.5 million. The catch is that "same-day" depends heavily on when you apply, how quickly you submit documents, and whether your business meets basic revenue and trading history thresholds.
Managing Payroll and Materials: A Complete Guide for Australian Business Owners
Australian businesses lose an average of 8 hours per week on manual payroll and materials tracking. Payroll and materials management involves systematically tracking employee wages, benefits, and raw material costs to ensure accurate financial reporting, tax compliance, and cash flow control.
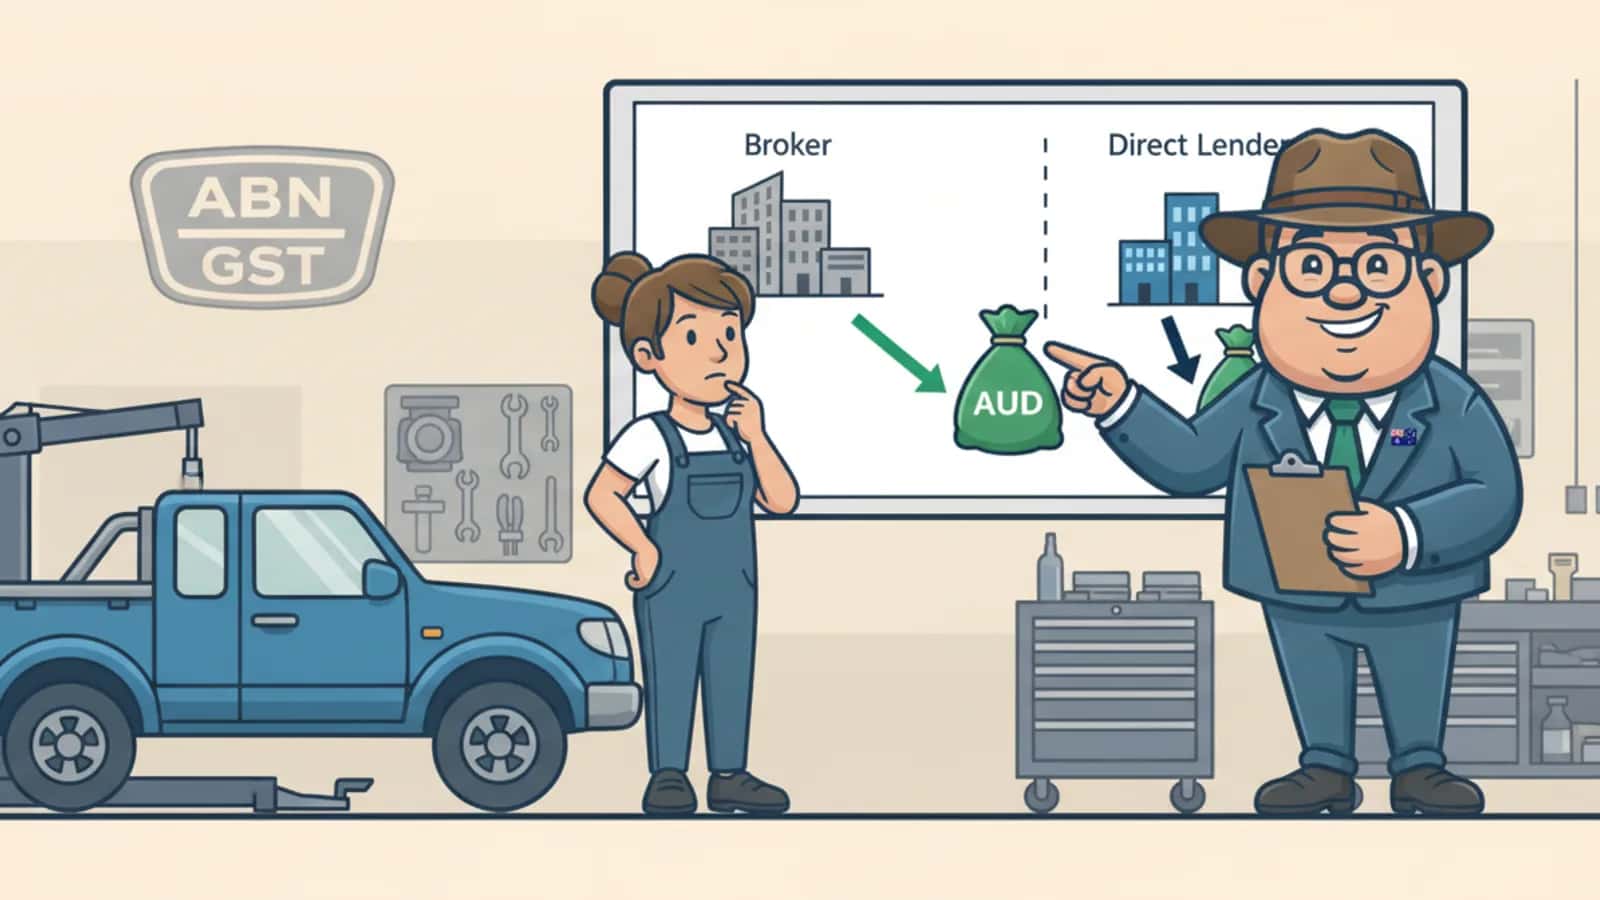
Business Loan Broker vs Direct Lender in Australia: Which Route Is More Likely to Save You Money?
For most Australian small businesses, using a broker tends to produce better loan terms and higher approval odds — but it's not always the cheapest path once you factor in commissions. Going direct to a lender is faster if you already know which product suits you and your credit profile is strong.
How to Compare Business Loan Rates and Fees: A Step-by-Step Guide for Australian SMEs
Comparing business loan rates and fees in Australia means looking beyond the headline interest rate. You need to weigh the comparison rate, all upfront and ongoing fees, and the total cost of credit over the loan term.
How Global Interest Rates Affect Australian Business Loan Costs
Australian business loan rates are driven mainly by the RBA cash rate, lenders' funding costs and the risk of the individual application. Global rate changes can influence wholesale funding and the Australian dollar, but there is no fixed or guaranteed pass-through.

Business Loan Refinancing in Australia: When It Makes Sense to Switch Lenders (and When It Doesn't)
Business loan refinancing in Australia means replacing your existing facility with a new loan — usually to get a lower rate, better terms, or improved cash flow. It makes sense when the savings outweigh the exit costs.
Business Loans questions
The important details before you check eligibility.
What should a business compare before choosing a loan?
Compare total repayment cost, repayment frequency, eligibility criteria, security requirements, application speed, and whether the loan fits the way the business earns revenue.
How much can a business typically borrow?
Loan sizes vary widely by lender and depend on turnover, trading history, and affordability. Facilities commonly range from a few thousand to several hundred thousand pounds, with larger amounts available to established businesses.
Do I need to be a homeowner to get a business loan?
Not always. Some lenders ask for a personal guarantee that can take homeownership into account, but many business loans don't require you to own property.
Will checking my options affect my credit score?
An initial eligibility check is often a soft search that doesn't affect your score. A full application may involve a hard credit check, so confirm with the lender before you proceed.
How quickly can the money arrive?
It depends on the lender and how ready your paperwork is. Some online lenders approve and fund within a day or two, while traditional lenders can take longer.
Are business loan requirements the same in every market?
No. Eligibility, terminology, credit checks, and lender expectations vary by market, so each Funding Fred guide is written for the relevant country.
Ready when you are
Explore Australian business loan options
Start a short eligibility check for Australian business funding options. It only takes about 2 minutes, with no hard credit check to start.