
Australian Business Loan Guides
Compare business loans by cost, eligibility, repayment, and speed — plain-English guides to help you choose the right lender and apply with confidence.
Business loans explained
Use these guides to compare business loan options by cost, eligibility, repayment structure, speed, and lender fit before you apply — so you walk into a funding decision already knowing the answers.
What to compare before you borrow
Total cost of borrowing
Look past the headline rate at the APR, arrangement fees, and the total amount repayable over the full term.
Repayment structure
Fixed monthly payments, a share of card takings, or a flexible facility — match it to how your revenue actually arrives.
Eligibility & trading history
Most lenders weigh time trading, turnover, and credit profile. Knowing yours up front avoids wasted applications.
Speed to funding
Some lenders pay out in 24–48 hours, others take weeks. If timing matters, prioritise lenders built for speed.
Security & guarantees
Check whether the loan is secured against assets or needs a personal guarantee before you commit.
Early repayment terms
If you might clear the balance early, confirm whether there are exit fees or interest savings.
Latest guides
Australia's Business Loan Market Right Now: What Rising Funding Costs Mean for Small Borrowers
Australia's business loan market right now is under real pressure. The RBA lifted the cash rate to 4.35% in May 2026, pushing average small business lending rates to 7.18% for outstanding loans.
How Global Interest Rates Affect Australian Business Loan Costs
Australian business loan rates are driven mainly by the RBA cash rate, lenders' funding costs and the risk of the individual application. Global rate changes can influence wholesale funding and the Australian dollar, but there is no fixed or guaranteed pass-through.
Australian Business Loan Approval Checklist: What Lenders Want Before They Say Yes
The Australian business loan approval checklist covers five core areas: a valid ABN, minimum trading history (usually 6–12 months), consistent monthly revenue, clean financial statements, and acceptable credit history.
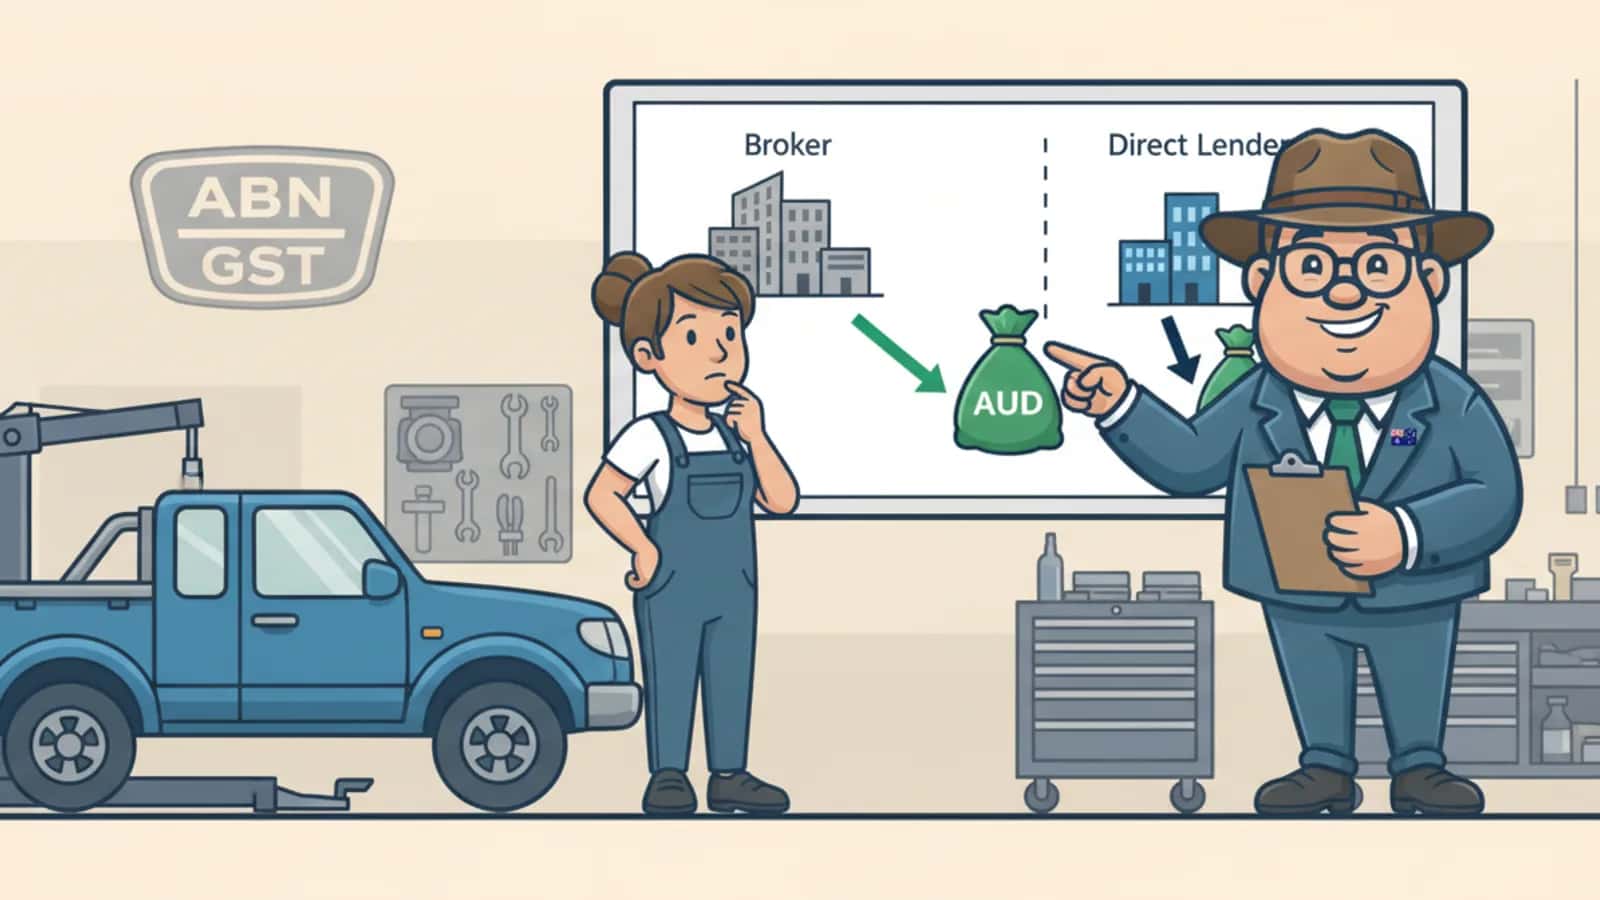
Business Loan Broker vs Direct Lender in Australia: Which Route Is More Likely to Save You Money?
For most Australian small businesses, using a broker tends to produce better loan terms and higher approval odds — but it's not always the cheapest path once you factor in commissions. Going direct to a lender is faster if you already know which product suits you and your credit profile is strong.
Chartered Financial Planner, CFPs and Your Business Loan: How Professional Advice Changes What You Can Borrow
A Chartered Financial Planner (CFP) can directly increase how much your business qualifies to borrow by improving your financial ratios, structuring your application correctly, and positioning your business against lender benchmarks before you apply.
ATO Debt Payment Plan vs Business Loan: How Australian SMEs Should Decide
Australian SMEs facing tax debt now face a critical choice: ATO payment plans have become significantly more expensive since July 2025 when the General Interest Charge (GIC) became non-deductible, while business loans may offer cheaper alternatives for larger debts.
Investing vs Borrowing: When Australian Business Owners Should Use Profits Instead of Loans
The right choice between reinvesting profits and taking on debt depends on three things: the cost of borrowing versus your expected return, your current cash reserves, and how urgent the opportunity is.
Business Loans for Regional and Rural Australian SMEs: Unique Funding Challenges and Solutions
Business loans for regional and rural Australian SMEs work differently from city lending — fewer local bank branches, income that swings with seasons, and industries banks consider higher risk all make approval harder. But specialist online lenders and government programs have closed much of that gap.
Business Loans for Women Entrepreneurs in Australia: Banks, Online Lenders, Grants and Support Networks
Women entrepreneurs in Australia can access business loans through major banks (Westpac has committed $1 billion specifically to female founders), online lenders, government-backed grants, and dedicated support programs. Loan amounts range from $5,000 to several million dollars.
Business Loans questions
The important details before you check eligibility.
What should a business compare before choosing a loan?
Compare total repayment cost, repayment frequency, eligibility criteria, security requirements, application speed, and whether the loan fits the way the business earns revenue.
How much can a business typically borrow?
Loan sizes vary widely by lender and depend on turnover, trading history, and affordability. Facilities commonly range from a few thousand to several hundred thousand pounds, with larger amounts available to established businesses.
Do I need to be a homeowner to get a business loan?
Not always. Some lenders ask for a personal guarantee that can take homeownership into account, but many business loans don't require you to own property.
Will checking my options affect my credit score?
An initial eligibility check is often a soft search that doesn't affect your score. A full application may involve a hard credit check, so confirm with the lender before you proceed.
How quickly can the money arrive?
It depends on the lender and how ready your paperwork is. Some online lenders approve and fund within a day or two, while traditional lenders can take longer.
Are business loan requirements the same in every market?
No. Eligibility, terminology, credit checks, and lender expectations vary by market, so each Funding Fred guide is written for the relevant country.
Ready when you are
Explore Australian business loan options
Start a short eligibility check for Australian business funding options. It only takes about 2 minutes, with no hard credit check to start.