
Business Loans. Without the Fuss.
Compare business loans by cost, eligibility, repayment, and speed — plain-English guides to help you choose the right lender and apply with confidence.
Business loans explained
Use these guides to compare business loan options by cost, eligibility, repayment structure, speed, and lender fit before you apply — so you walk into a funding decision already knowing the answers.
What to compare before you borrow
Total cost of borrowing
Look past the headline rate at the APR, arrangement fees, and the total amount repayable over the full term.
Repayment structure
Fixed monthly payments, a share of card takings, or a flexible facility — match it to how your revenue actually arrives.
Eligibility & trading history
Most lenders weigh time trading, turnover, and credit profile. Knowing yours up front avoids wasted applications.
Speed to funding
Some lenders pay out in 24–48 hours, others take weeks. If timing matters, prioritise lenders built for speed.
Security & guarantees
Check whether the loan is secured against assets or needs a personal guarantee before you commit.
Early repayment terms
If you might clear the balance early, confirm whether there are exit fees or interest savings.
Latest guides
How to Improve Your Chances of Business Loan Approval in Australia
To improve your chances of business loan approval in Australia, focus on five things before you apply: clean up your credit file, demonstrate consistent cash flow, organise your financial records, borrow an amount that matches your revenue, and choose a lender whose criteria actually fits your business.
How to Use Your Business Balance Sheet to Strengthen Loan Applications
Your balance sheet is one of the first documents a lender looks at when assessing a business loan. It shows what your business owns, what it owes, and how much equity is left over.
Investing vs Borrowing: When Australian Business Owners Should Use Profits Instead of Loans
The right choice between reinvesting profits and taking on debt depends on three things: the cost of borrowing versus your expected return, your current cash reserves, and how urgent the opportunity is.
Open Banking and Bank-Statement Loans: How Australian Lenders Assess Cash Flow
Australian lenders now use open banking technology to assess cash flow in real-time, replacing traditional bank statement uploads with secure, automated data feeds. This speeds up loan decisions from weeks to days, while giving lenders deeper insights into business revenue patterns, seasonal trends, and actual cash position.
Personal Guarantees, PPSR Security and Collateral in Australian Business Loans
Personal guarantees, PPSR security and collateral in Australian business loans are three different risk management tools lenders use. A personal guarantee makes you personally liable for business debt, PPSR security gives lenders a registered claim over business assets, and collateral is specific property pledged against the loan.
Trade Finance Australia: Funding Imports, Exports and Supplier Payments
Trade finance in Australia provides working capital to pay suppliers upfront, fund imports from overseas, and bridge the payment gap between orders and cash flow. Most lenders offer 90-180 day terms with decisions within 24-48 hours, covering up to 100% of supplier invoices without requiring property security.
Australia's Business Loan Market Right Now: What Rising Funding Costs Mean for Small Borrowers
Australia's business loan market right now is under real pressure. The RBA lifted the cash rate to 4.35% in May 2026, pushing average small business lending rates to 7.18% for outstanding loans [1].
Australian Business Loan Approval Checklist: What Lenders Want Before They Say Yes
The Australian business loan approval checklist covers five core areas: a valid ABN, minimum trading history (usually 6–12 months), consistent monthly revenue, clean financial statements, and acceptable credit history.
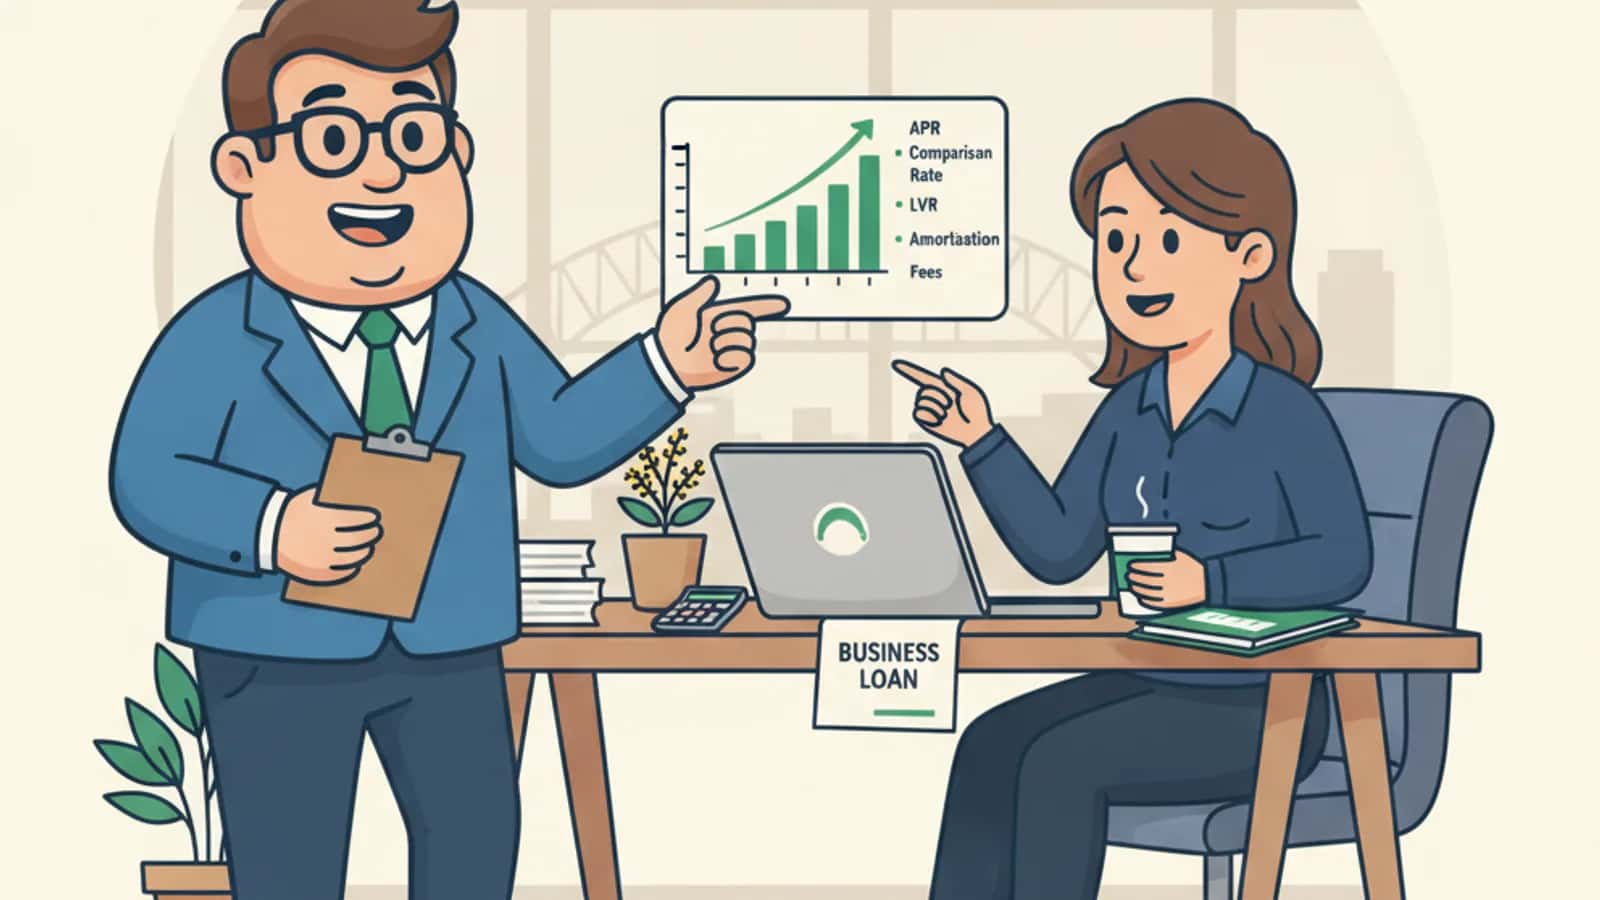
Australian Business Loan Terms Explained: APR, Comparison Rates, LVR, Amortisation and Fees
Australian business loan terms like APR, comparison rates, LVR, and amortisation directly affect how much a loan costs and whether an application gets approved.
Business Loans questions
The important details before you check eligibility.
What should a business compare before choosing a loan?
Compare total repayment cost, repayment frequency, eligibility criteria, security requirements, application speed, and whether the loan fits the way the business earns revenue.
How much can a business typically borrow?
Loan sizes vary widely by lender and depend on turnover, trading history, and affordability. Facilities commonly range from a few thousand to several hundred thousand pounds, with larger amounts available to established businesses.
Do I need to be a homeowner to get a business loan?
Not always. Some lenders ask for a personal guarantee that can take homeownership into account, but many business loans don't require you to own property.
Will checking my options affect my credit score?
An initial eligibility check is often a soft search that doesn't affect your score. A full application may involve a hard credit check, so confirm with the lender before you proceed.
How quickly can the money arrive?
It depends on the lender and how ready your paperwork is. Some online lenders approve and fund within a day or two, while traditional lenders can take longer.
Are business loan requirements the same in every market?
No. Eligibility, terminology, credit checks, and lender expectations vary by market, so each Funding Fred guide is written for the relevant country.
Ready when you are
Explore Australian business loan options
Start a short eligibility check for Australian business funding options. It only takes about 2 minutes, with no hard credit check to start.