
US Business Loan Guides
Compare business loans by cost, eligibility, repayment, and speed — plain-English guides to help you choose the right lender and apply with confidence.
Business loans explained
Use these guides to compare business loan options by cost, eligibility, repayment structure, speed, and lender fit before you apply — so you walk into a funding decision already knowing the answers.
What to compare before you borrow
Total cost of borrowing
Look past the headline rate at the APR, arrangement fees, and the total amount repayable over the full term.
Repayment structure
Fixed monthly payments, a share of card takings, or a flexible facility — match it to how your revenue actually arrives.
Eligibility & trading history
Most lenders weigh time trading, turnover, and credit profile. Knowing yours up front avoids wasted applications.
Speed to funding
Some lenders pay out in 24–48 hours, others take weeks. If timing matters, prioritise lenders built for speed.
Security & guarantees
Check whether the loan is secured against assets or needs a personal guarantee before you commit.
Early repayment terms
If you might clear the balance early, confirm whether there are exit fees or interest savings.
Latest guides
SBA 7(a) Loans Explained: Eligibility Requirements and Application Guide
The SBA 7(a) program supports eligible business purposes through approved lenders. The maximum loan amount is $5 million; eligibility, collateral, pricing and terms depend on the use of funds, business profile and lender underwriting.
SBA 7(a) vs Online Business Loan: Which Route Is Faster, Cheaper and More Realistic?
SBA 7(a) loans can offer longer terms and regulated rate caps but require fuller documentation. Online business loans may reach a decision sooner, but cost and repayment frequency vary widely.
SBA Microloans for Small Businesses: When a $50K Loan Makes More Sense Than a Bank Loan
SBA microloans offer up to $50,000 with 8-13% interest rates and seven-year repayment terms through nonprofit intermediaries, making them ideal for small businesses that need working capital but don't qualify for traditional bank loans.
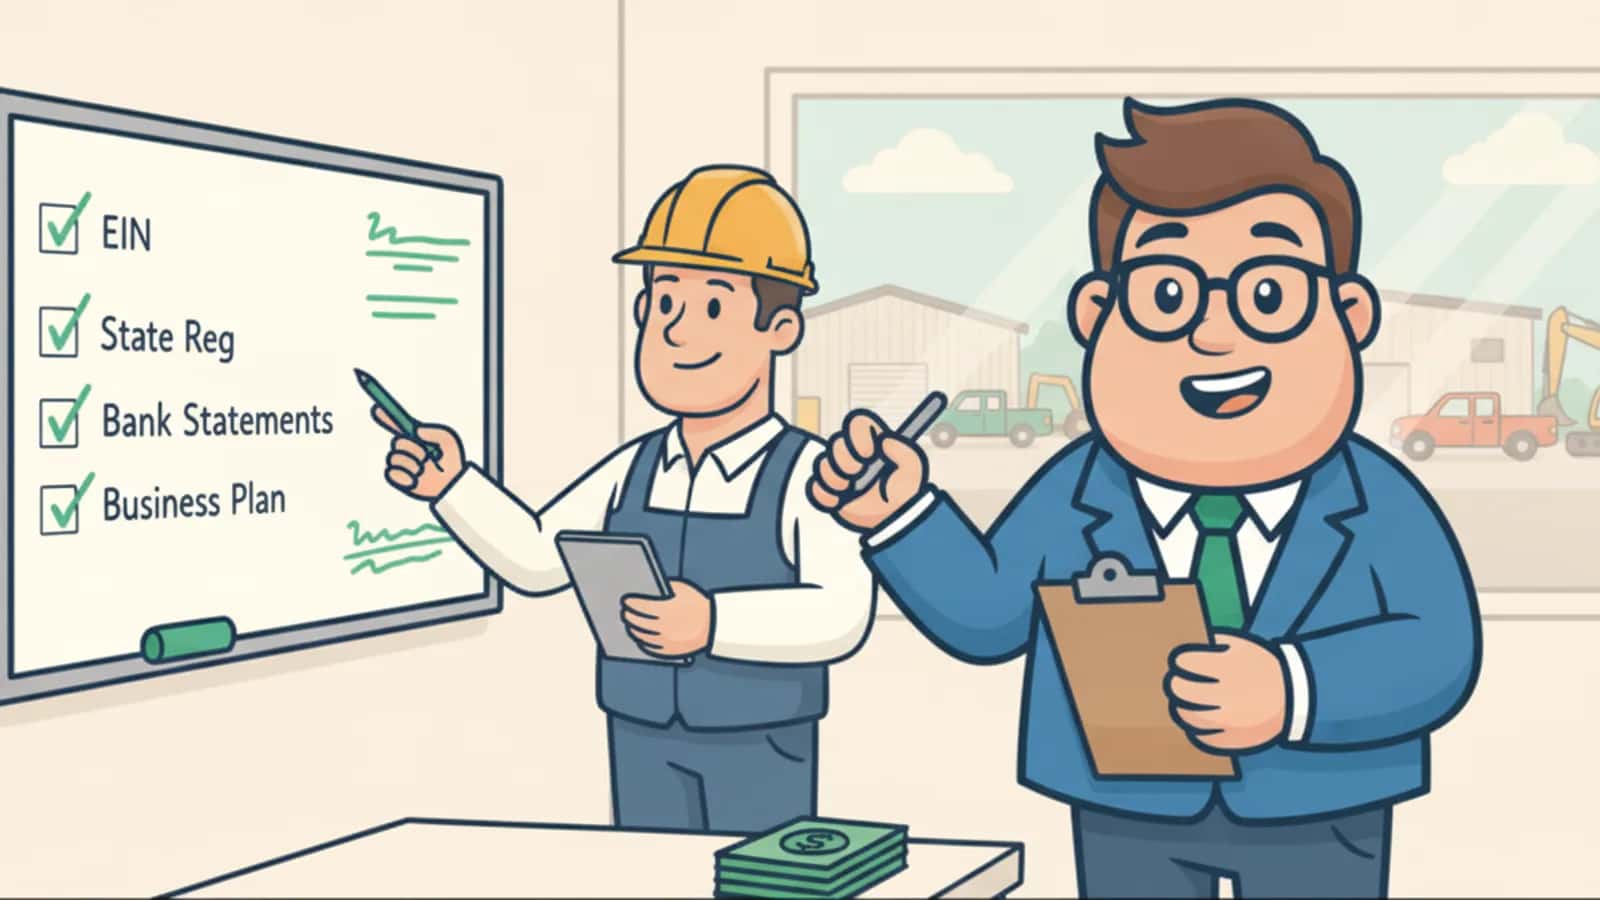
US Business Loan Approval Checklist: What Lenders Ask For Before They Say Yes
Lenders evaluate business loan applications based on five core criteria: personal credit score (typically 600+ for alternative lenders, 680+ for banks), business revenue ($15,000+ monthly for non-bank lenders, $25,000+ for traditional banks), time in business (6 months minimum for alternative funding, 2+ years for banks), debt service coverage ratio of 1.15-1.35, and comprehensive financial documentation including bank statements, tax returns, and business formation documents.
Business Loan Uses: How American Small Businesses Deploy Working Capital in 2026
Business loans serve multiple strategic purposes for American small businesses, from managing cash flow gaps and purchasing inventory to funding payroll, equipment purchases, and growth initiatives. The most effective use depends on your business model, revenue patterns, and specific operational needs.
Business Credit Cards vs Business Loans: When Each Makes Sense
Business credit cards work best for everyday expenses, short-term cash flow gaps, and purchases you can pay off monthly. Business loans suit larger investments like equipment, inventory, or expansion where you need structured payments over months or years at lower interest rates.
UCC Liens and Personal Guarantees in US Small Business Lending: What Business Owners Need to Know
UCC liens give lenders legal claims on business assets like equipment and inventory, while personal guarantees make business owners personally responsible for loan repayment. Most small business loans require both, creating dual layers of security for lenders but significant risk exposure for borrowers.
Business Loans questions
The important details before you check eligibility.
What should a business compare before choosing a loan?
Compare total repayment cost, repayment frequency, eligibility criteria, security requirements, application speed, and whether the loan fits the way the business earns revenue.
How much can a business typically borrow?
Loan sizes vary widely by lender and depend on turnover, trading history, and affordability. Facilities commonly range from a few thousand to several hundred thousand pounds, with larger amounts available to established businesses.
Do I need to be a homeowner to get a business loan?
Not always. Some lenders ask for a personal guarantee that can take homeownership into account, but many business loans don't require you to own property.
Will checking my options affect my credit score?
An initial eligibility check is often a soft search that doesn't affect your score. A full application may involve a hard credit check, so confirm with the lender before you proceed.
How quickly can the money arrive?
It depends on the lender and how ready your paperwork is. Some online lenders approve and fund within a day or two, while traditional lenders can take longer.
Are business loan requirements the same in every market?
No. Eligibility, terminology, credit checks, and lender expectations vary by market, so each Funding Fred guide is written for the relevant country.
Ready when you are
Explore US business funding options
Start a short eligibility check for US business funding options. It only takes about 2 minutes, with no hard credit check to start.