
Bridging Loan Guides
Bridging loans explained for UK property buyers and businesses — compare loan-to-value, speed, exit routes, fees, and regulated-use checks before you apply.
Bridging loans explained
Use these guides to understand how short-term bridging finance works, what lenders check, and how property value, deal stage, exit route, and personal credit can affect your options.
What to compare before using a bridging loan
Loan-to-value
Compare the loan amount against the current or completed property value, and check how fees are added to the facility.
Exit strategy
Lenders want a credible route to repay the bridge, such as selling the property, refinancing, or selling another asset.
Speed and deal stage
Auction purchases, chain breaks, and live offers can need faster completion, so match the lender to your deadline.
Regulated use
If you or a close family member will live in the property, the loan may be regulated and the lender pool can change.
Fees and retained interest
Compare arrangement fees, valuation fees, legal costs, monthly or retained interest, and any exit fees.
Latest guides
Bridging Loan Costs UK: Rates and Fees Explained for 2026
Bridging loan costs in the UK range from 0.55% to 1.5% per month in interest, plus arrangement fees of around 2% of the loan amount. Total costs depend on your loan-to-value ratio, property type, and exit strategy, with typical annual rates equivalent to 6.6% to 18% APR.
Auction Bridging Loans: How to Complete Fast Without Losing Your Deposit
Auction bridging loans are short-term property finance facilities designed to help buyers complete auction purchases within the strict 28-day deadline.
Light Refurbishment vs Heavy Refurbishment Bridging Finance: Complete UK Guide 2026
Property investors lose deals every day because they choose the wrong refurbishment finance. Light refurbishment bridging loans fund cosmetic improvements like new kitchens and bathrooms without structural changes, while heavy refurbishment finance covers major works including extensions and structural modifications.
Mixed-Use Property Bridging Finance: Shops, Flats and Semi-Commercial Assets
Mixed-use property bridging finance provides short-term funding from £25k to £25m+ for properties combining residential and commercial elements, such as shops with flats above.
Probate Bridging Loans: Funding Inherited Property Sales and Repairs
Probate bridging loans provide short-term finance to beneficiaries who need immediate funds to repair, maintain, or sell inherited properties while waiting for probate completion.
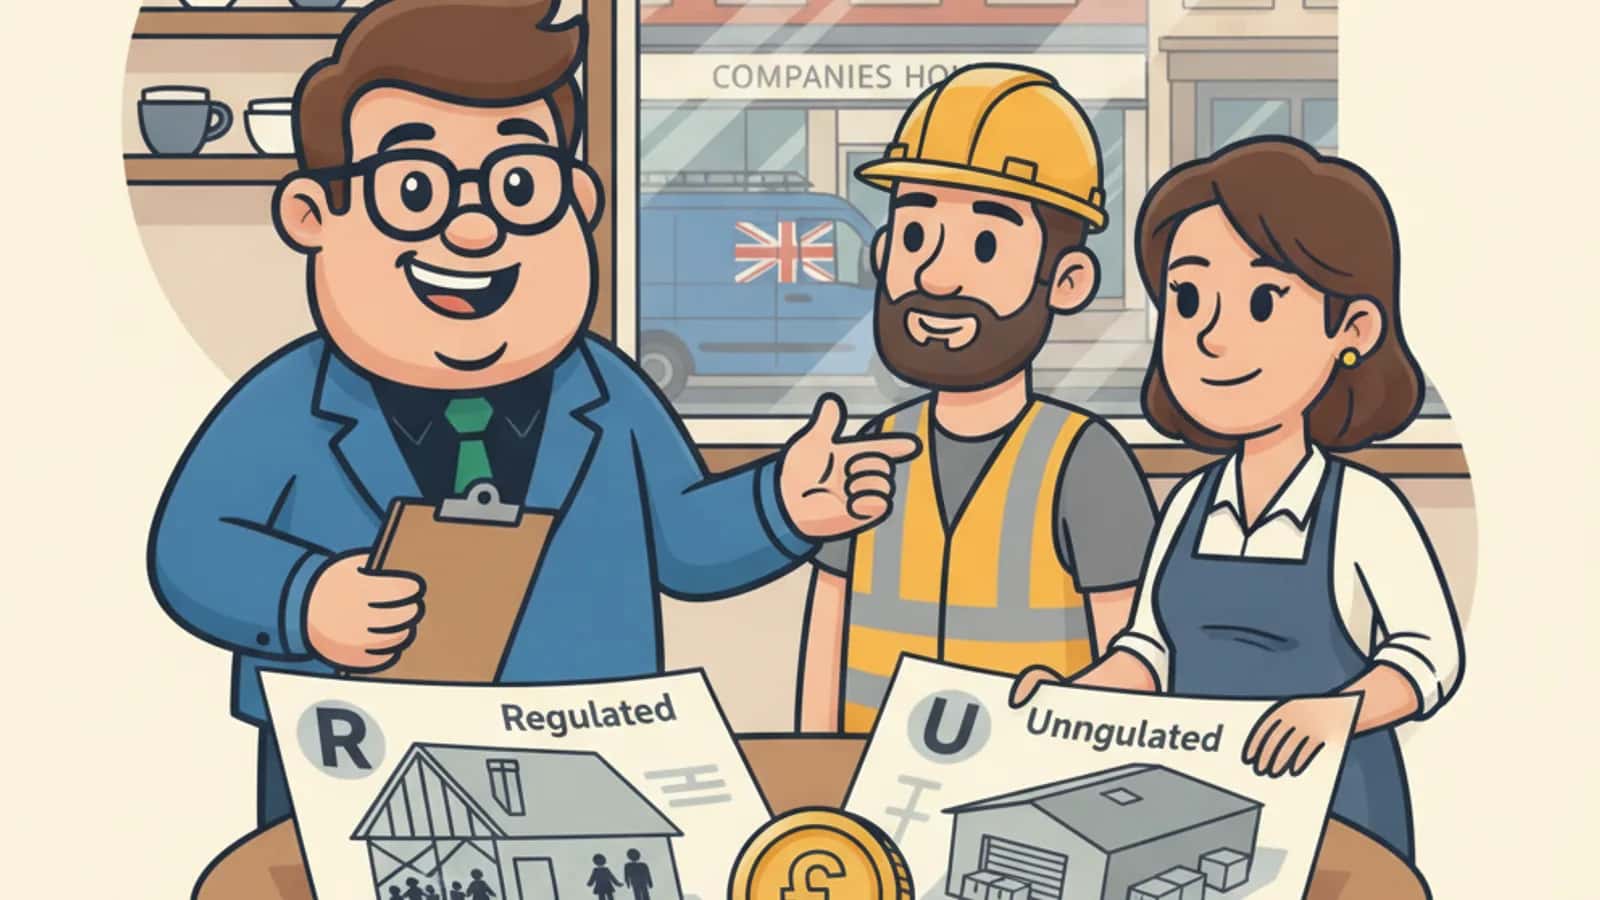
Regulated vs Unregulated Bridging Loans: What UK Borrowers Need to Know
The key difference between regulated and unregulated bridging loans lies in their intended use: regulated loans apply to properties you'll live in, while unregulated loans cover investment properties and commercial deals.
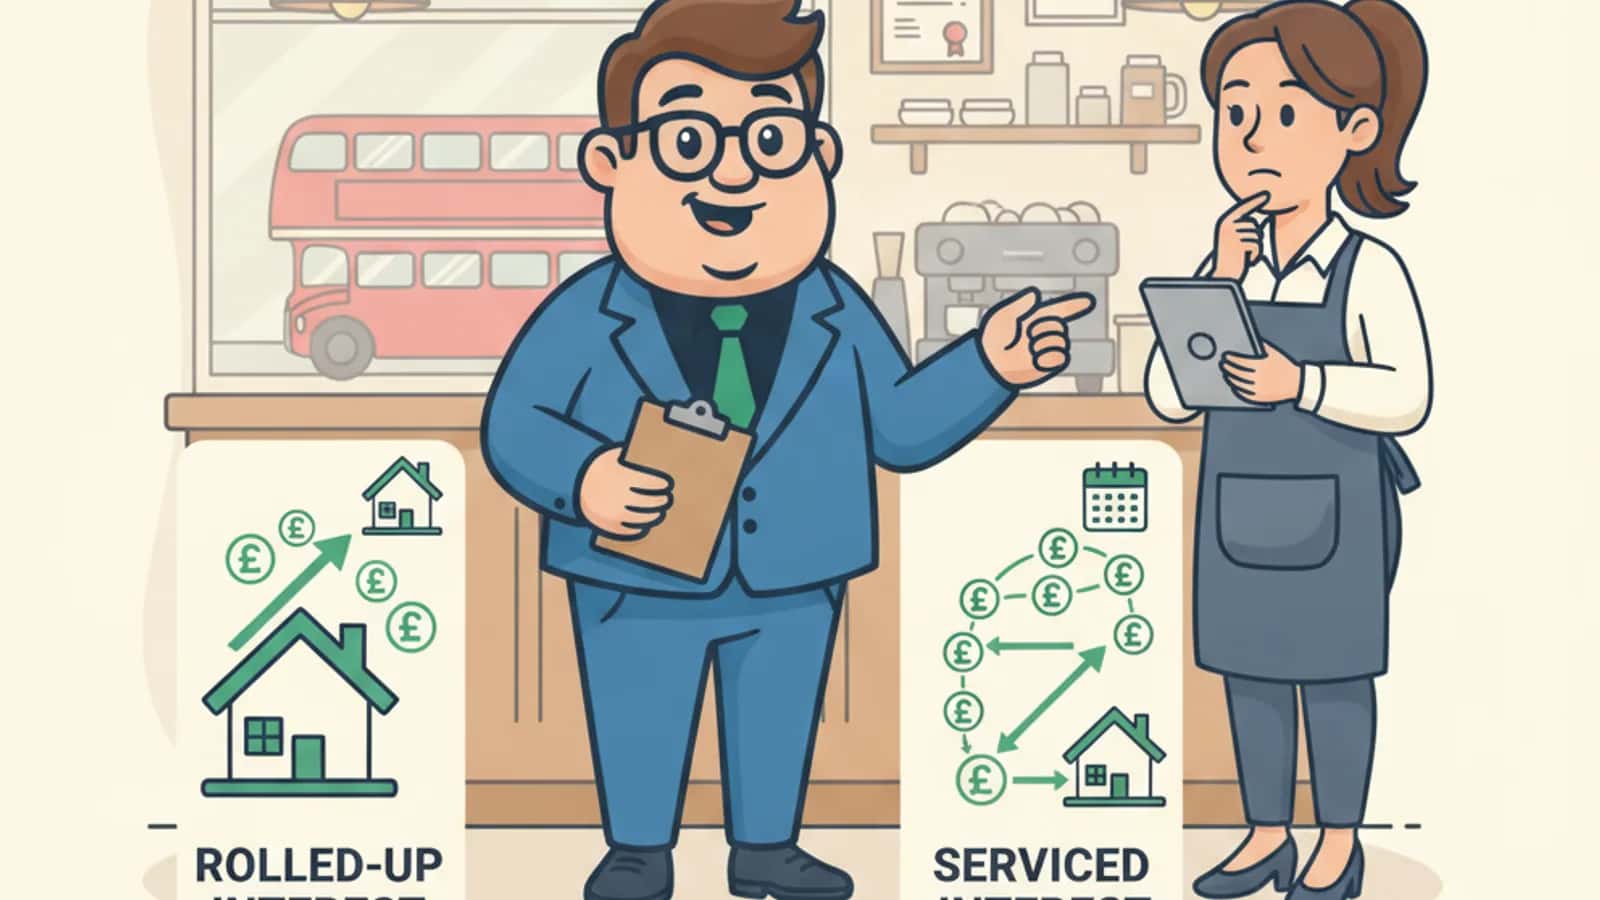
Rolled-Up vs Serviced Interest on Bridging Loans: Which Is Better?
Both rolled-up and serviced interest options cost the same total amount if rates and terms are identical, the difference is when you pay and how it affects your cash flow and loan balance.

What Is a Bridging Loan? Complete UK Guide for Borrowers
A bridging loan is short-term finance secured on property or land and intended to be repaid through a defined exit, usually a sale, refinance or another known source. Interest may be paid monthly, retained or added to the balance.
Bridge-to-Development Finance: Funding a Site Before Planning or Construction Starts
Property developers face a critical funding gap: securing sites before planning permission is granted. Bridge-to-development finance fills this gap by providing short-term funding to purchase land or buildings while developers navigate the planning process, typically for 12-24 months at rates from 0.75% to 2% monthly.
Bridging Loans questions
The important details before you check eligibility.
What is a bridging loan?
A bridging loan is short-term property finance used to bridge a funding gap, often for purchases, auction deadlines, chain breaks, refinance, or light refurbishment.
How quickly can bridging finance complete?
Timelines vary by lender, valuation, legal work, and complexity. Straightforward cases can move quickly, while regulated or unusual cases usually need more checks.
What exit strategy do bridging lenders accept?
Common exits include selling the property, refinancing to a longer-term mortgage, or repaying from another asset sale. The exit needs to be realistic for the loan term.
Can a bridging loan be used for development?
Some bridging loans support light refurbishment, but projects needing planning or heavier works may fit development finance better.
Ready when you are
Explore bridging loan options
Answer a few questions to see whether a bridging loan could fit your property deal. It only takes about 2 minutes, with no hard credit check to start.