
Invoice Finance Guides
Invoice financing explained for UK businesses — compare advance rates, fees, debtor checks, recourse terms, and cash-flow fit before using unpaid invoices for funding.
Invoice financing explained
Use these guides to understand how invoice finance can release cash tied up in unpaid B2B invoices, what lenders check, and how fees, advance rates, and contract terms affect cash flow.
What to compare before financing invoices
Advance rate
Check what percentage of each invoice can be released upfront and when the remaining balance is paid.
Fees and total cost
Compare service fees, discount charges, minimum fees, and any setup or exit costs before judging the headline rate.
Debtor quality
Invoice finance providers often assess who owes the invoices, payment history, concentration risk, and whether the debtors are businesses.
Recourse terms
Understand whether your business remains liable if a customer does not pay, and what happens when invoices become overdue.
Control and customer contact
Some facilities are confidential, while others involve the provider managing collections. Match the structure to your customer relationships.
Latest guides
Invoice Financing for Businesses with Poor Credit History: Options Beyond Traditional Lenders
Invoice financing for businesses with poor credit history offers a genuine route to working capital when banks say no. Because specialist lenders assess your customers' ability to pay — not your own credit file — past defaults, CCJs, or a thin credit history are far less likely to block your application.
Invoice Finance for UK SMEs: Using Your Sales Ledger as a Dynamic Funding Pool
Invoice finance for UK SMEs turns unpaid invoices into immediate working capital by advancing up to 90% of an invoice's face value within 24–48 hours of raising it. Rather than waiting 30, 60, or 90 days for customers to pay, businesses access funds tied up in their sales ledger as a revolving, scalable facility.
How UK SMEs Are Using Invoice Finance in 2026 to Combat Late Payments and Working Capital Gaps
UK SMEs are owed an estimated £26 billion in late B2B payments at any one time, with the average invoice running 23.4 days past agreed terms. In 2026, more businesses are turning to invoice finance — releasing 80–90% of invoice value within 24 hours — to close working capital gaps without waiting 30, 60, or 90 days to be paid.

Invoice Finance for Agencies and Consultancies: Funding Project Work on 30-90 Day Terms
Invoice finance for agencies and consultancies converts unpaid client invoices into immediate cash flow, typically advancing 80-95% of invoice value within 24 hours.
Invoice Financing Costs in the UK: Typical Fees, Discount Rates and Total Interest Explained for 2026
Invoice financing in the UK typically costs between 1% and 2.4% of annual turnover when you combine service fees and discount charges. Service fees run from 0.5% to 3% of turnover, while discount rates sit at roughly 1.5% to 3% above the Bank of England base rate — producing effective annual rates of around 5.25% to 6.75% at current base rates.

Bad Debts and Invoice Financing: What Happens If Your Customer Doesn't Pay in the UK?
When a customer doesn't pay under an invoice finance arrangement in the UK, what happens next depends entirely on the type of facility you have. With recourse invoice factoring, the unpaid debt returns to you.
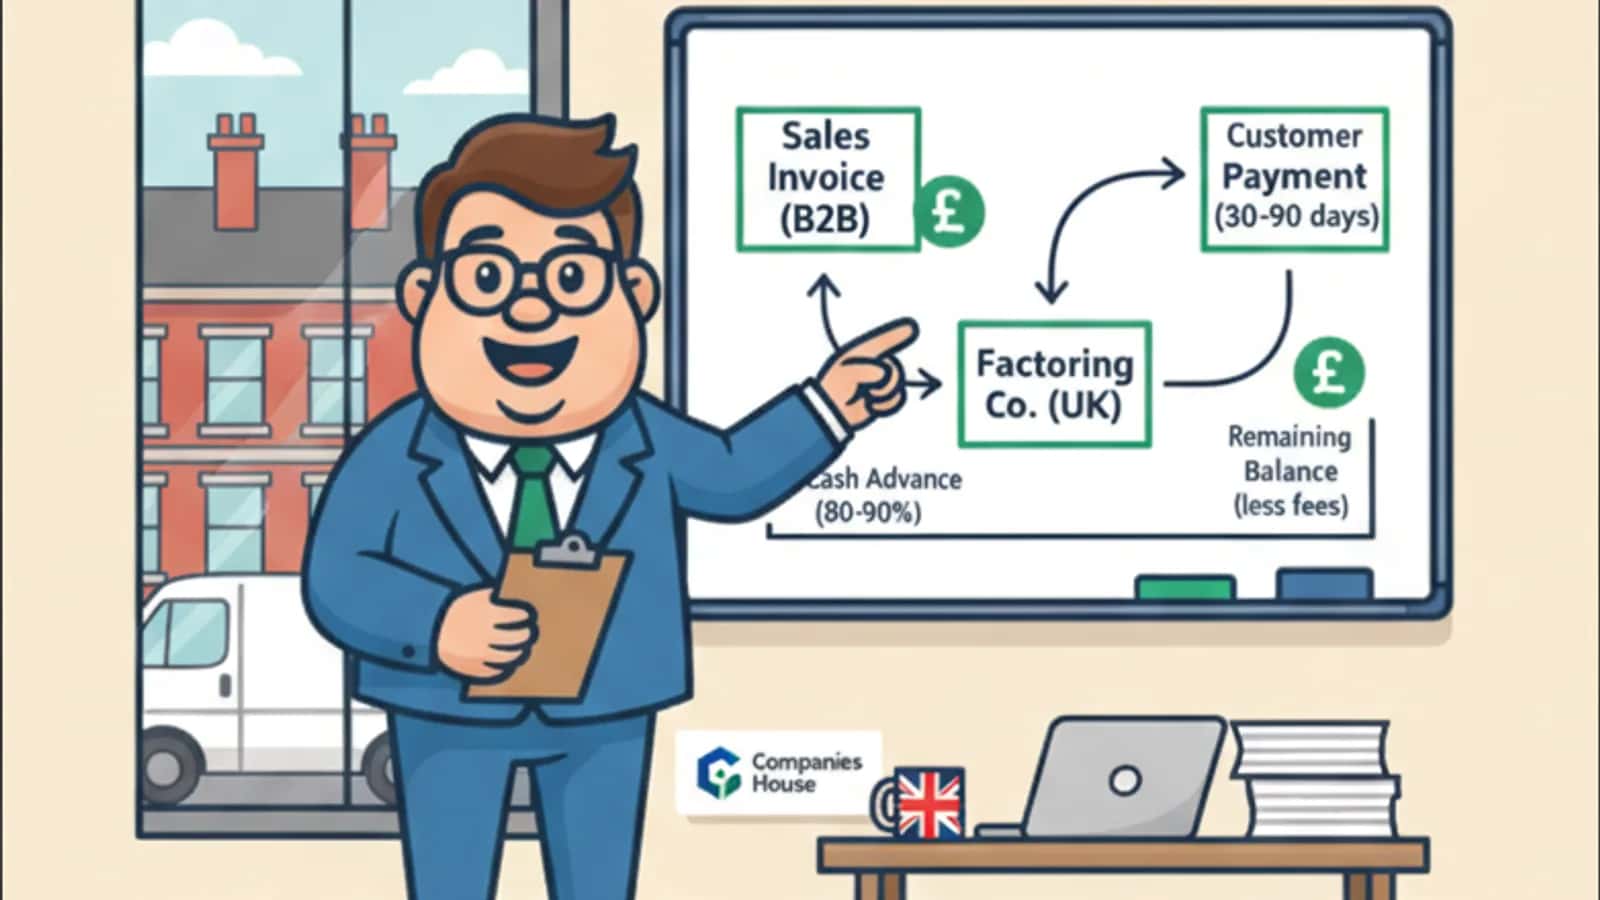
Debt Factoring UK: How Invoice Factoring Works and What It Costs
Debt factoring is a funding arrangement where a business sells its unpaid invoices to a factoring company in exchange for an upfront cash advance, usually a large percentage of the invoice value, paid within a day or two of approval.
Invoice Factoring for UK Businesses: Bank‑Branded Facilities vs Specialist Providers Compared
Invoice factoring lets UK businesses sell unpaid invoices to a finance provider and receive up to 90–95% of the invoice value within 24 hours — sometimes faster.
Invoice Financing for Seasonal UK Businesses: Using Your Sales Ledger to Manage Cash Flow Peaks and Troughs
Invoice financing for seasonal UK businesses lets you unlock cash tied up in unpaid invoices during your busiest trading periods, rather than waiting 30, 60, or 90 days for customers to pay. Instead of taking on a fixed-term loan you repay year-round, you draw against your sales ledger when it's full and scale back when it isn't.
Invoice Financing questions
The important details before you check eligibility.
What is invoice financing?
Invoice financing lets a business access cash against unpaid invoices instead of waiting for customers to pay. The provider advances part of the invoice value, then the balance is settled after payment, minus fees.
Which businesses use invoice finance?
It is usually used by businesses that invoice other businesses on payment terms, such as 30, 60, or 90 days. Providers normally review the invoice book and debtor quality before offering a facility.
How much can a business release from invoices?
Advance rates vary by provider, debtor profile, invoice value, and risk. Many facilities advance a percentage of approved invoices rather than the full invoice amount.
Is invoice financing the same as a business loan?
No. A business loan is usually a fixed borrowing facility with scheduled repayments. Invoice finance is linked to unpaid invoices and customer payment cycles.
Ready when you are
Explore invoice finance options
Answer a few questions to see whether invoice finance could help release cash tied up in unpaid invoices. It only takes about 2 minutes, with no hard credit check to start.