
Business Finance Guides
Plain-English guides to UK business loans, asset finance, invoice financing, and business credit cards. Compare lenders, check what you'll qualify for, and walk into a funding decision already knowing the answers.
Business Loans
View all
HMRC Time to Pay: How It Works and When a Business Loan Fits Better
An HMRC Time to Pay arrangement lets a business or individual spread a tax bill into instalments, typically over up to 12 months, instead of paying it all at once. HMRC agrees to it case by case, based on whether the business is genuinely viable but short on cash right now, and interest keeps accruing on the unpaid balance the whole time.
How Much Business Loan Can I Get? How UK Lenders Size Your Loan Amount
How much business loan can I get depends on four things: your turnover, your profit, your ability to cover the monthly repayment (affordability), and whether you offer security. Unsecured loans in the UK typically top out well below secured loans, and many lenders benchmark unsecured lending at roughly a fifth to a quarter of annual turnover.
Business Loan With a CCJ: What UK Lenders Check and How to Improve Your Chances
Yes, you can get a business loan with a CCJ in the UK, but mainstream banks usually decline once a County Court Judgment shows up on a credit check. Specialist and alternative lenders look past the judgment itself and weigh its age, size, and whether it's satisfied or unsatisfied, alongside your current trading performance.
Asset Finance
View all
Asset Finance Brokers UK: Banks, Specialists and Brokers Compared
Asset finance brokers match businesses with lenders that fund vehicles, plant and equipment, comparing hire purchase, finance lease and other structures across a panel of providers instead of a single balance sheet. Banks suit businesses with existing banking relationships and straightforward credit profiles.
Business Car Finance: Buying or Leasing a Car Through a Limited Company
Business car finance lets a limited company buy or lease a car through hire purchase, a finance lease, or business contract hire instead of the director funding it personally.
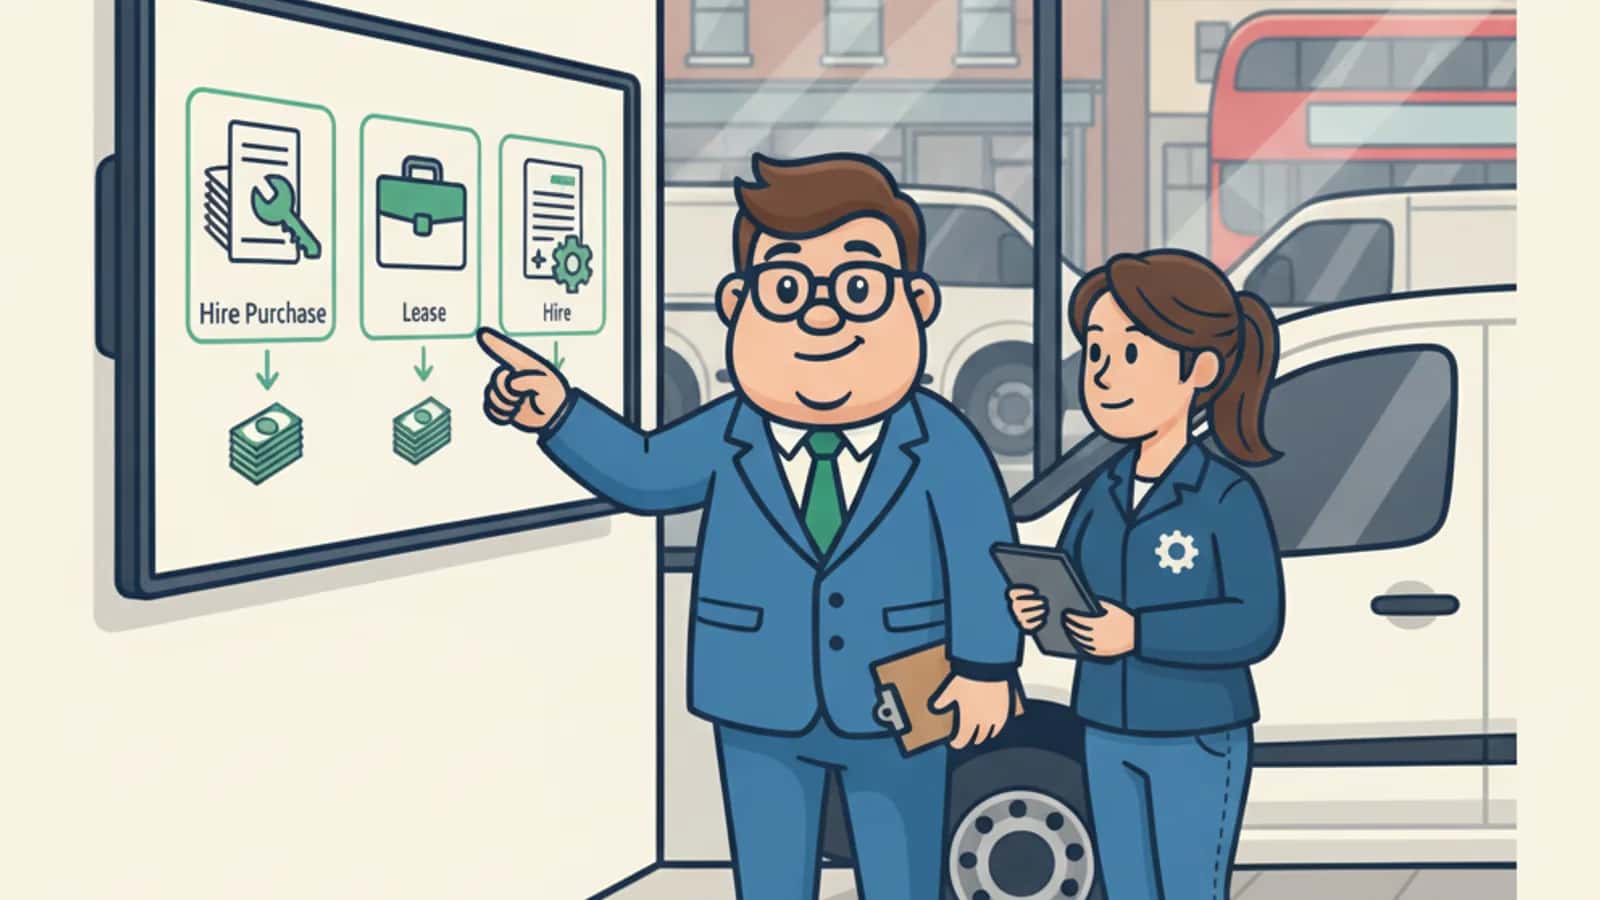
Business Van Finance: Hire Purchase, Lease and Contract Hire Compared
Business van finance lets a sole trader, limited company or new business spread the cost of a van over time instead of paying cash upfront.
Invoice Financing
View all
Asset Based Lending UK: Combining Invoices, Stock and Plant in One Facility
Asset based lending (ABL) lets a UK business borrow against several assets at once, unpaid invoices, stock, plant and machinery, and sometimes property, inside a single facility with one borrowing base instead of separate loans.
Invoice Financing for Businesses with Poor Credit History: Options Beyond Traditional Lenders
Invoice financing for businesses with poor credit history offers a genuine route to working capital when banks say no. Because specialist lenders assess your customers' ability to pay — not your own credit file — past defaults, CCJs, or a thin credit history are far less likely to block your application.
Invoice Finance for UK SMEs: Using Your Sales Ledger as a Dynamic Funding Pool
Invoice finance for UK SMEs turns unpaid invoices into immediate working capital by advancing up to 90% of an invoice's face value within 24–48 hours of raising it. Rather than waiting 30, 60, or 90 days for customers to pay, businesses access funds tied up in their sales ledger as a revolving, scalable facility.
Bridging Loans
View all
Commercial Property Bridging Loans for UK Business Owners: Fast Funding Solutions
Commercial property bridging loans for UK business owners provide short-term funding from £25,000 to £60 million, typically for 1-24 months, with interest rates starting from 0.75% per month. These loans enable rapid property acquisitions, refinancing, and development projects when traditional bank lending moves too slowly for time-sensitive opportunities.
How Fast Can a Bridging Loan Complete? UK Timelines, Documents and Delays
Brokers most often quote 2-4 weeks for a straightforward bridging loan, and the fastest cases complete in 7-14 days. The 2025 industry average was longer, at 43 days (about six weeks, an eight-year low), so plan for around six weeks unless your documents, valuation and solicitors are ready from the start.
Why Bridging Loans Get Declined: Weak Exits, Valuation Gaps and Affordability Issues
Bridging loans get declined primarily due to weak exit strategies that lack specific repayment plans, significant valuation gaps between borrower expectations and lender assessments, and affordability concerns where borrowers can't demonstrate sufficient reserves to cover potential delays or additional costs.
Development Finance
View all
Cost Overruns in Development Finance: How Contingency and Reforecasting Work
Cost overruns in development finance occur when actual project expenses exceed approved budgets, forcing developers to inject additional equity or secure supplementary funding.
Development Finance for First-Time Developers: What Lenders Need to See
First-time developers can access development finance from approximately 30-40 specialist lenders in the UK, but they'll face stricter criteria including higher equity requirements (minimum 20%), lower loan-to-value ratios (50-60% LTGDV), and higher interest rates (8-12% annually).
Development Finance for SPVs: Why Property Schemes Use Special Purpose Vehicles
Over 80% of UK development finance applications in 2026 now use Special Purpose Vehicle (SPV) structures rather than personal or main company borrowing.
Business Credit Cards
View all
How to Set Business Credit Card Spending Limits for Employees: A Practical UK Guide
To set business credit card spending limits for employees, assign role-based limits through your card provider's admin dashboard, document the limits in a written card policy, and use per-transaction, daily, or monthly controls to match each employee's actual spend needs.
Employee Business Credit Cards: Liability, Controls and Expense Rules
Employee business credit cards let UK companies issue cards directly to staff, with the business controlling spend limits, merchant categories, and reporting. Under a corporate liability model, the company is responsible for all charges, not the individual employee.
Are Business Credit Card Cashback and Rewards Worth It for UK Companies in 2026?
Yes, business credit card cashback and rewards are worth it for most UK companies, but only if the card's annual fee doesn't swallow the returns, and you're clearing the balance each month. For businesses spending £2,000 or more monthly on card-eligible costs, the maths usually works in your favour.
Ready when you are
See what funding your business could get
Start a short eligibility check and compare selected business funding options. It only takes about 2 minutes, with no hard credit check to start.