Asset Finance Brokers UK: Banks, Specialists and Brokers Compared
Asset finance brokers match businesses with lenders that fund vehicles, plant and equipment, comparing hire purchase, finance lease and other structures across a panel of providers instead of a single balance sheet. Banks suit businesses with existing banking relationships and straightforward credit profiles.
Quick answer
Asset finance brokers match businesses with lenders that fund vehicles, plant and equipment, comparing hire purchase, finance lease and other structures across a panel of providers instead of a single balance sheet. Banks suit businesses with existing banking relationships and straightforward credit profiles. Specialist lenders and asset finance brokers suit businesses that need speed, flexible deposits, or a lender comfortable with their asset type, sector or credit history. The right route depends on how urgent the need is and how standard the asset and applicant look to a credit committee.
Key takeaways
- Asset finance brokers do not lend their own money. They assess the request, then place it with a lender from their panel of asset finance providers.
- Banks tend to suit established businesses with strong trading history. Specialist lenders and brokers tend to suit newer businesses, unusual assets, or time-pressured purchases.
- Brokers are usually paid commission by the lender, built into the finance cost, not charged as a separate upfront fee in most cases, always ask for this in writing.
- UK asset finance new business passed £30bn annually in 2026, with SME lending growing faster than lending to larger corporates in several months this year.
- Always check a broker or lender on the FCA Register before signing anything.
- No broker or lender can promise guaranteed approval, no credit checks, or instant funding, pricing, eligibility and timing vary by applicant and asset.
- Construction Equipment, Commercial Vehicles, and Plant & Machinery are the asset categories seeing the strongest growth in 2026 lending data.
What Do Asset Finance Brokers Do?
Asset finance brokers act as the link between a business that needs to fund an asset and a panel of lenders that might approve it. They take one application, check it against lender criteria, then route it to whichever provider is the best fit, rather than the business applying separately to five different lenders.
In practice, a broker will usually:
- Gather details on the business, the asset, and the deposit available.
- Run an initial eligibility check, often without a hard credit search.
- Shortlist lenders likely to approve the deal based on asset type, sector and credit profile.
- Present terms for hire purchase, finance lease or other structures side by side.
- Handle documentation and liaise with the lender through to drawdown.
Bank vs Specialist Lender vs Broker: Which Suits Which Business?
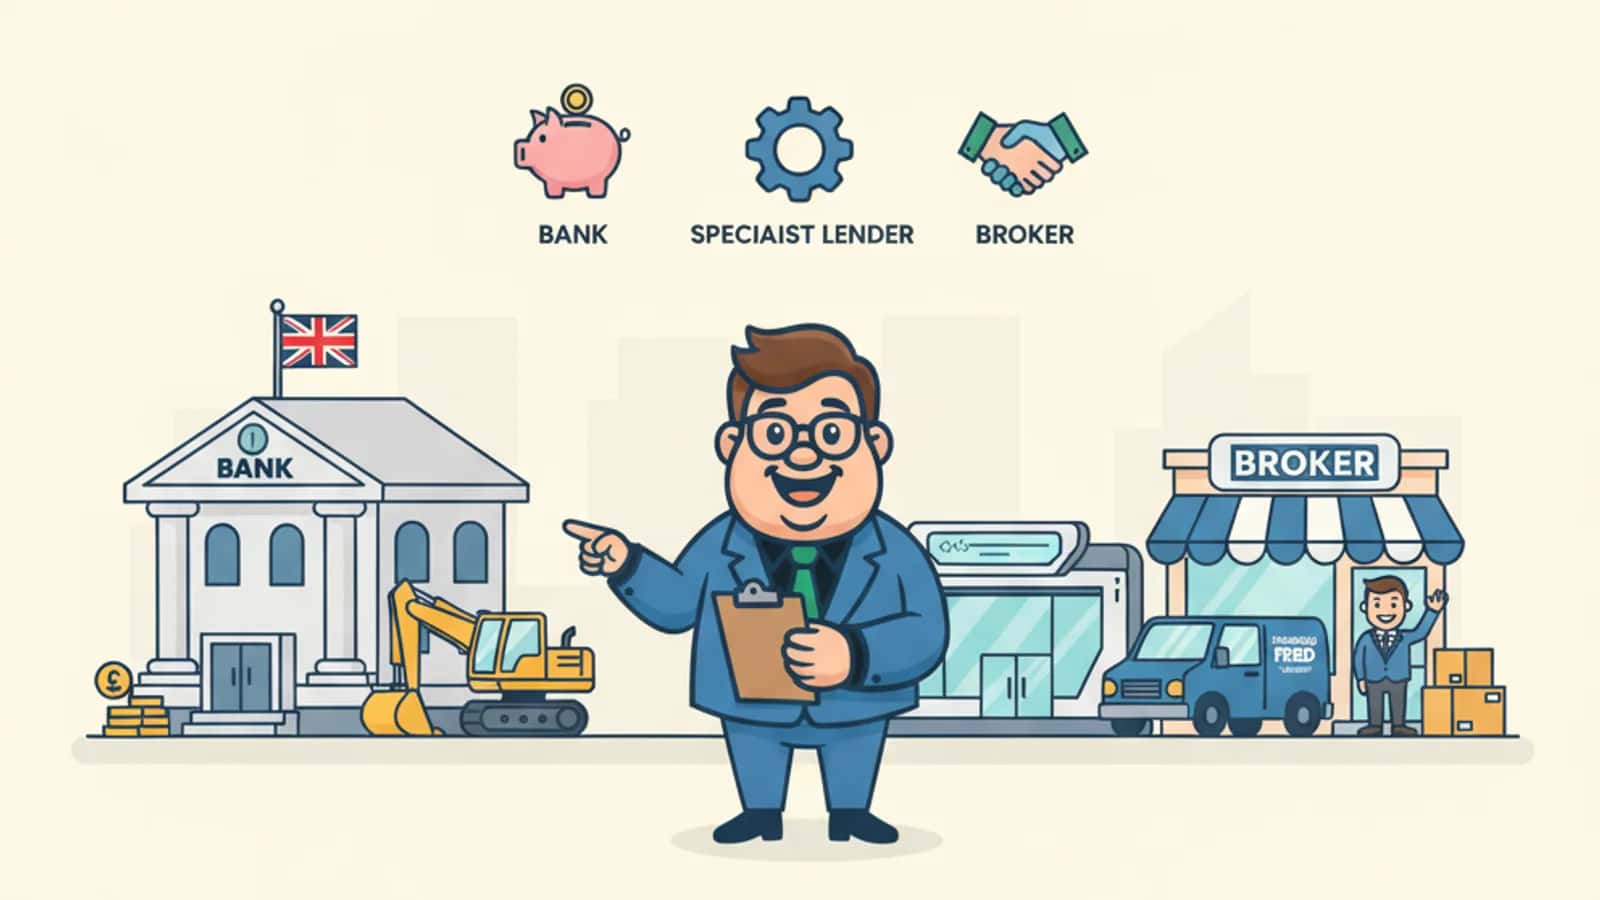
The three main routes to asset finance are a bank, a specialist (non-bank) lender, or a broker who accesses both. Choose a bank if the business already banks there and has strong, straightforward credit. Choose a specialist lender or a broker if the asset, sector, credit history or timeline falls outside a bank's standard appetite.
High street bank
- Typical strength
- Competitive pricing for strong credit; existing relationship can speed things up
- Typical limitation
- Narrower appetite for used assets, start-ups, or non-standard sectors; slower decisioning for complex deals
- Best suited to
- Established businesses with clean accounts and a standard asset request
Specialist lender
- Typical strength
- Deep knowledge of a specific asset class (plant, HGVs, CNC machinery); more flexible on deposit and structure
- Typical limitation
- Access usually requires going direct or being introduced; fewer but more tailored products
- Best suited to
- Businesses with niche assets, thinner trading history, or past credit issues
Asset finance broker
- Typical strength
- Compares multiple lenders in one application; can match deposit flexibility and timeline to the project
- Typical limitation
- Relies on lender appetite and panel breadth; service quality varies by firm
- Best suited to
- Businesses that want to compare hire purchase, finance lease and other options quickly without applying lender by lender
A decision rule worth keeping: if the asset is standard (a mainstream van, for example) and the business has three years of clean accounts, a bank is often worth trying first. If the asset is used, specialist, or the business needs a fast decision with a flexible deposit, a broker working across specialist partners is usually the quicker path. Platforms built for this, such as Funding Fred's asset finance service, run a short eligibility check against a specialist partner panel so businesses can see options from hire purchase to finance lease without multiple separate applications.
Industry data for 2026 shows why this distinction matters: plant and machinery finance new business rose 9% year-on-year in July, and business equipment finance rose 6%, while new lending to SMEs grew faster than lending to larger corporates in several months of the year. That shift towards SME and hard-asset lending is exactly the segment where specialist lenders and brokers tend to add the most value over a generalist bank.
How Are Asset Finance Brokers Paid?
Most asset finance brokers are paid commission by the lender once a deal completes, built into the cost of the finance rather than billed to the customer as a separate invoice. Some brokers also charge an arrangement or facility fee directly to the business, this should always be disclosed upfront and in writing. Related guide: Invoice Finance Brokers UK.
What to ask before signing anything:
- Is the broker paid commission by the lender, a fee by the business, or both?
- Will the commission structure affect which lender gets recommended?
- Is there a broker fee separate from the lender's arrangement fee?
- Can the commission and fee be confirmed in writing before the agreement is signed?
This is not a minor detail. Following the Supreme Court's 2024 rulings on undisclosed commissions in motor finance, FCA guidance and industry commentary in 2026 have placed renewed focus on commission transparency across asset and motor finance, with brokers under pressure to document and disclose how they are paid. The FCA's Consumer Duty also requires brokers to show that products recommended are fair value for the customer, not just the most commission-generative option.
What Are the Biggest Asset Finance Companies in the UK?
The UK asset finance market includes high street banks, captive finance arms of equipment manufacturers, independent specialist lenders, and intermediary brokers, rather than a single dominant provider. Total UK asset finance new business exceeded £30bn annually in 2026, making it one of the most widely used forms of external business finance.
A few structural points worth knowing, without ranking named firms:
- The broker market has consolidated around larger, nationwide intermediaries. The Finance Connect Asset Finance Broker 40 Report expanded from 30 to 40 firms in 2026, reflecting growth in scaled broker distribution.
- Specialist lenders are growing quickly in parts of the market banks serve less actively, one specialist asset finance provider reported 53% year-on-year growth in new business over the first seven months of 2026.
- Established lenders continue to invest in broker relationships: Investec Asset Finance marked 20 years in the market in 2026 with an event for more than 80 broker principals and directors, underlining how important broker channels remain to larger lenders.
- New products launched in 2026, including structured asset-backed funding aimed at SMEs via brokers, and asset-based lending propositions combining receivables, plant and property into one facility, show the market is diversifying rather than consolidating around a handful of names.
Rather than chasing a "best lender" list, it is usually more useful to compare quotes for a specific asset and read provider reviews covering the structures most relevant to the request, hire purchase, finance lease, or contract hire.
How Do You Check a Provider Is Authorised?
Check any asset finance broker or lender on the Financial Conduct Authority's Register before sharing financial information or signing an agreement. The FCA Register confirms whether a firm is authorised, what activities it can carry out, and whether it has any restrictions or warnings against it.
Steps to verify a provider:
- Search the firm's name or reference number on the FCA Register (register.fca.org.uk).
- Confirm the permissions listed include credit broking or consumer credit lending, as relevant.
- Check the firm's registered details match what it has told the business, same company name, same address.
- Cross-check the company at Companies House to confirm it is actively trading and not newly dissolved or dormant.
- Ask directly how the firm is paid and request this in writing before signing.
Most larger business asset finance agreements fall outside the Consumer Credit Act's regulated threshold, but credit broking activity still requires FCA authorisation, and hire purchase or conditional sale agreements under certain thresholds for individuals and small partnerships are regulated. If a firm cannot confirm its FCA status clearly, that is a reason to walk away.
Can You Get Asset Finance Without a Broker?
Yes. A business can apply directly to a bank or specialist lender without using a broker. This usually makes sense when the business already has a strong relationship with its bank, the asset is standard, and there is time to apply to more than one lender separately if the first says no.
Going direct can work well when:
- The business banks with a lender that already offers asset finance and understands its accounts.
- The asset and deal size are straightforward (a mainstream commercial vehicle, for example).
- There is no urgent deadline, so multiple applications and credit searches are not a problem.
A broker tends to add more value when:
- Time is tight, a contract has been won, or equipment has broken down.
- The asset is unusual, used, or outside a typical bank's comfort zone.
- The business wants to compare hire purchase against finance lease terms without multiple hard searches.
- Credit history includes defaults, CCJs, or limited trading history.
For businesses weighing this up, this guide comparing hire purchase and finance lease structures is a useful next read either way.
What Equipment Can You Finance Through Asset Brokers?
Asset finance brokers typically cover three broad categories: Construction Equipment, Commercial Vehicles, and Plant & Machinery, alongside soft assets like IT and office equipment. Lender appetite and deposit requirements vary by category, asset age, and business sector.
Construction Equipment, Excavators, diggers, telehandlers, generators and site cabins. 2026 data shows plant and machinery finance new business rising 9% year-on-year in July, a sign specialist lenders are actively competing for this category.
Commercial Vehicles, Vans, HGVs, trailers and specialist fleet vehicles, new or used. Used commercial vehicle and used car finance volumes rose strongly through 2026 as businesses manage higher borrowing costs by buying used rather than new.
Plant & Machinery, CNC machines, production lines, cranes and manufacturing equipment, often funded through hire purchase where the business wants eventual ownership, or finance lease where flexibility matters more. Business equipment finance new business also grew year-on-year in mid-2026.
For a wider view of asset categories and how they're typically structured, see this breakdown of what can be financed through asset finance, and this guide on the main types of asset finance available in the UK.
How Long Does Asset Finance Approval Take?
Approval timeframes vary by lender, asset type, deposit level, and how complete the application is, there is no fixed turnaround that applies across the market. A straightforward application with full documentation ready tends to move faster than one missing financials or proof of the asset.
What tends to speed things up:
- A completed initial eligibility check before a formal application.
- Accounts, bank statements and asset details ready in advance (see the asset finance application checklist for the standard list lenders ask for).
- A clear invoice or quote for the asset from the seller.
- A realistic deposit offer matched to the lender's typical range for that asset type.
What tends to slow things down:
- Incomplete company accounts or missing bank statements.
- Ambiguity over who legally owns or will own the asset.
- Unusual company structures that need extra underwriting checks.
Decision rule: if the business has a hard deadline, a contract start date, a broken-down machine, flag that urgency at the first enquiry so the broker can prioritise lenders known for faster decisioning on that asset type.
Asset Finance Broker for Bad Credit
Some brokers and specialist lenders will consider businesses with past defaults, CCJs, or a director with adverse personal credit history, though terms, deposit requirements and lender appetite vary significantly case by case. No broker can promise guaranteed approval regardless of credit history.
Factors that typically influence outcomes:
- How recent and how serious the credit issue was.
- Whether the business has traded profitably since.
- The deposit the business can offer (a larger deposit can offset credit risk for some lenders).
- The resale value and usefulness of the asset as security.
This is one of the clearest cases where a broker's access to specialist partners matters: a bank is less likely to flex on a credit issue than a lender built specifically for higher-risk profiles. For more detail on what's realistic, read this guide on bad credit asset finance in the UK.
Independent Asset Finance Broker vs Tied Broker
An independent broker accesses multiple lenders and recommends based on fit; a tied broker is contractually linked to one lender or a small panel and can only offer their products. Independence generally gives a wider comparison, but a tied broker's single lender relationship can sometimes mean faster processing for deals that fit squarely within that lender's criteria.
Ask any broker directly:
- Is the firm tied to one lender, or does it work across an open panel?
- How many lenders could realistically be approached for this specific deal?
- Is the recommendation based on the best fit, or the only option available?
How to Become an Asset Finance Broker
Becoming an asset finance broker in the UK generally requires FCA authorisation for credit broking activities, relevant compliance infrastructure, and lender panel agreements, it is a regulated activity, not an informal referral business. Firms must register with the FCA, meet Consumer Duty obligations, and maintain clear commission disclosure practices.
Typical steps involved:
- Register the business with Companies House.
- Apply for FCA authorisation covering credit broking (and consumer credit activities if dealing with regulated agreements).
- Build compliance processes around fair value assessments and commission disclosure under Consumer Duty.
- Negotiate panel agreements with banks, captives and specialist lenders.
- Maintain ongoing FCA reporting and conduct obligations.
This is a longer regulatory process than many assume, and firms operating without FCA authorisation for credit broking are acting unlawfully, which is exactly why checking the FCA Register matters for any business shopping around for finance.
Asset Finance Broker Complaints: What to Watch For
The most common complaint triggers in asset finance brokerage involve undisclosed commission, pressure to sign quickly, and mismatched products sold for commission rather than fit. Any of these is a reason to pause and query the arrangement before signing.
Warning signs to watch for:
- Reluctance to confirm FCA authorisation or commission structure in writing.
- Pressure to sign the same day without time to compare terms.
- A recommended structure (hire purchase vs finance lease) that doesn't match how the business plans to use or dispose of the asset.
- No clear explanation of total cost, including fees, over the full term.
If a complaint does arise, the Financial Ombudsman Service can review disputes involving regulated credit broking activity, and the FCA Register shows whether a firm has had regulatory action taken against it. Increased scrutiny on commission disclosure following the 2024 Supreme Court rulings on undisclosed motor finance commissions has made this an active area of regulatory attention into 2026.
Common Mistakes When Using an Asset Finance Broker
The most frequent mistake is accepting the first quote without comparing structures or asking how the broker is paid. Others include underestimating deposit flexibility across lenders and not preparing documentation before applying, which slows the whole process down.
- Not comparing hire purchase against finance lease
- , the right structure depends on whether the business wants to own the asset at the end of the term or prefers flexibility.
- Skipping the FCA Register check
- , takes two minutes and confirms the firm is legitimate.
- Applying without the standard paperwork ready
- , see the asset finance application checklist for what lenders typically need.
- Assuming all brokers access the same lenders
- , panel breadth varies a lot between firms.
- Ignoring total cost over the term
- in favour of headline monthly payments.
Asset Finance Application Readiness Checklist
Before approaching a broker, specialist lender or bank, have these ready:
- Company registration details and trading history (Companies House number)
- Last 2-3 years of accounts, or management accounts for newer businesses
- 3-6 months of business bank statements
- Details of the asset: make, model, age, condition, and a quote or invoice from the seller
- Deposit amount available, or confirmation it needs to be flexible
- Director identification and proof of address
- Any existing finance agreements on other assets
Asset Finance. Without the Fuss. A contract won. A machine down. A fleet to grow. Whatever the trigger, a 2 min check compares Hire Purchase, Finance Lease and more across Specialist partners, No hard check to start, No obligation. Check Eligibility Now
Next steps for asset finance brokers
Choosing between a bank, a specialist lender and a broker comes down to timeline, asset type and credit profile, not brand recognition. Banks suit clean, standard deals. Specialist lenders and brokers suit everything else: tight deadlines, used assets, thinner trading history, or a need to compare hire purchase against finance lease without multiple hard credit searches.
Before applying anywhere, check the firm on the FCA Register, ask how it's paid, and get documentation ready using the asset finance application checklist. From there, a short eligibility check against a panel of specialist partners is usually the fastest way to see real options, not a single quote from a single lender. Explore the full range of asset finance guides for sector-specific detail, or run a no-obligation check to see what's realistically available for the asset in question.
Frequently asked questions
What Do Asset Finance Brokers Do?
Asset finance brokers act as the link between a business that needs to fund an asset and a panel of lenders that might approve it. They take one application, check it against lender criteria, then route it to whichever provider is the best fit, rather than the business applying separately to five different lenders.
Bank vs Specialist Lender vs Broker: Which Suits Which Business?
The three main routes to asset finance are a bank, a specialist (non-bank) lender, or a broker who accesses both. Choose a bank if the business already banks there and has strong, straightforward credit. Choose a specialist lender or a broker if the asset, sector, credit history or timeline falls outside a bank's standard appetite.
How Are Asset Finance Brokers Paid?
Most asset finance brokers are paid commission by the lender once a deal completes, built into the cost of the finance rather than billed to the customer as a separate invoice. Some brokers also charge an arrangement or facility fee directly to the business, this should always be disclosed upfront and in writing. Related guide: Invoice Finance Brokers UK.
What Are the Biggest Asset Finance Companies in the UK?
The UK asset finance market includes high street banks, captive finance arms of equipment manufacturers, independent specialist lenders, and intermediary brokers, rather than a single dominant provider. Total UK asset finance new business exceeded £30bn annually in 2026, making it one of the most widely used forms of external business finance.
How Do You Check a Provider Is Authorised?
Check any asset finance broker or lender on the Financial Conduct Authority's Register before sharing financial information or signing an agreement. The FCA Register confirms whether a firm is authorised, what activities it can carry out, and whether it has any restrictions or warnings against it.
Can You Get Asset Finance Without a Broker?
Yes. A business can apply directly to a bank or specialist lender without using a broker. This usually makes sense when the business already has a strong relationship with its bank, the asset is standard, and there is time to apply to more than one lender separately if the first says no.
Written by
The Funding Fred Editorial Team creates plain-English guides to help business owners understand funding options, eligibility, and application readiness before they compare finance options.
Reviewed by
UK business finance content reviewer
Robert reads our UK business finance guides before they go live, checking each one is accurate, easy to follow, and reflects how lending actually works today — not how a brochure says it should. He's listed on the FCA Register, approved as an SMF3 (AR) Executive Director at Switcha Limited, and connected to Lucky Growth Partners Ltd through its appointed representative relationship, so the regulated detail gets a properly qualified second read.
Sources
- Asset Finance Market Report
- Asset Finance Statistics
- Asset Finance
- Asset Finance New Business Grew By 2 In May 2026
- Reward Funding Launches Strategic Asset Finance
- Asset Finance
- Abf Ranked In Uks Top 40 Asset Finance Brokers
- Investec Marks 20 Years In Asset Finance With Broker Event
- Asset Finance New Business Grew By 9 In March 2026
- Asset Finance Uk