How to Compare Business Credit Cards: APR, Fees, Limits and Rewards
To compare business credit cards effectively, look beyond the headline APR. For most UK businesses, the credit limit, approval speed, fee structure, and spend controls matter more than a fraction of a percentage point on interest.
Quick answer
To compare business credit cards effectively, look beyond the headline APR. For most UK businesses, the credit limit, approval speed, fee structure, and spend controls matter more than a fraction of a percentage point on interest. Run a no-obligation eligibility check first, then compare offers side by side on the factors that actually affect your cash flow.
Key takeaways
- APR on business credit cards is typically higher than personal cards, but most businesses that clear their balance monthly pay zero interest, the limit and fee structure matter more
- Annual fees can be worth paying if the cashback or rewards offset the cost; run the numbers against your actual monthly spend
- Credit limits on business cards range from £1,000 to £250,000+ depending on the provider, your business financials, and trading history
- Hidden fees, foreign transaction charges, cash advance fees, late payment penalties, add up fast and rarely appear in headline comparisons
- Employee cards, virtual cards, and spend controls are features that reduce admin and stop overspend, not just nice-to-haves
- Funding Fred's 2-minute eligibility check involves no hard credit search and matches you with leading card providers based on your business profile
- Business credit cards do not carry Section 75 consumer protection, but chargeback rights and provider purchase protection may still apply
- Switching cards every one to two years is worth reviewing, limits, fees, and reward rates change, and your business needs change too
What Is the Difference Between Business and Personal Credit Card APR?
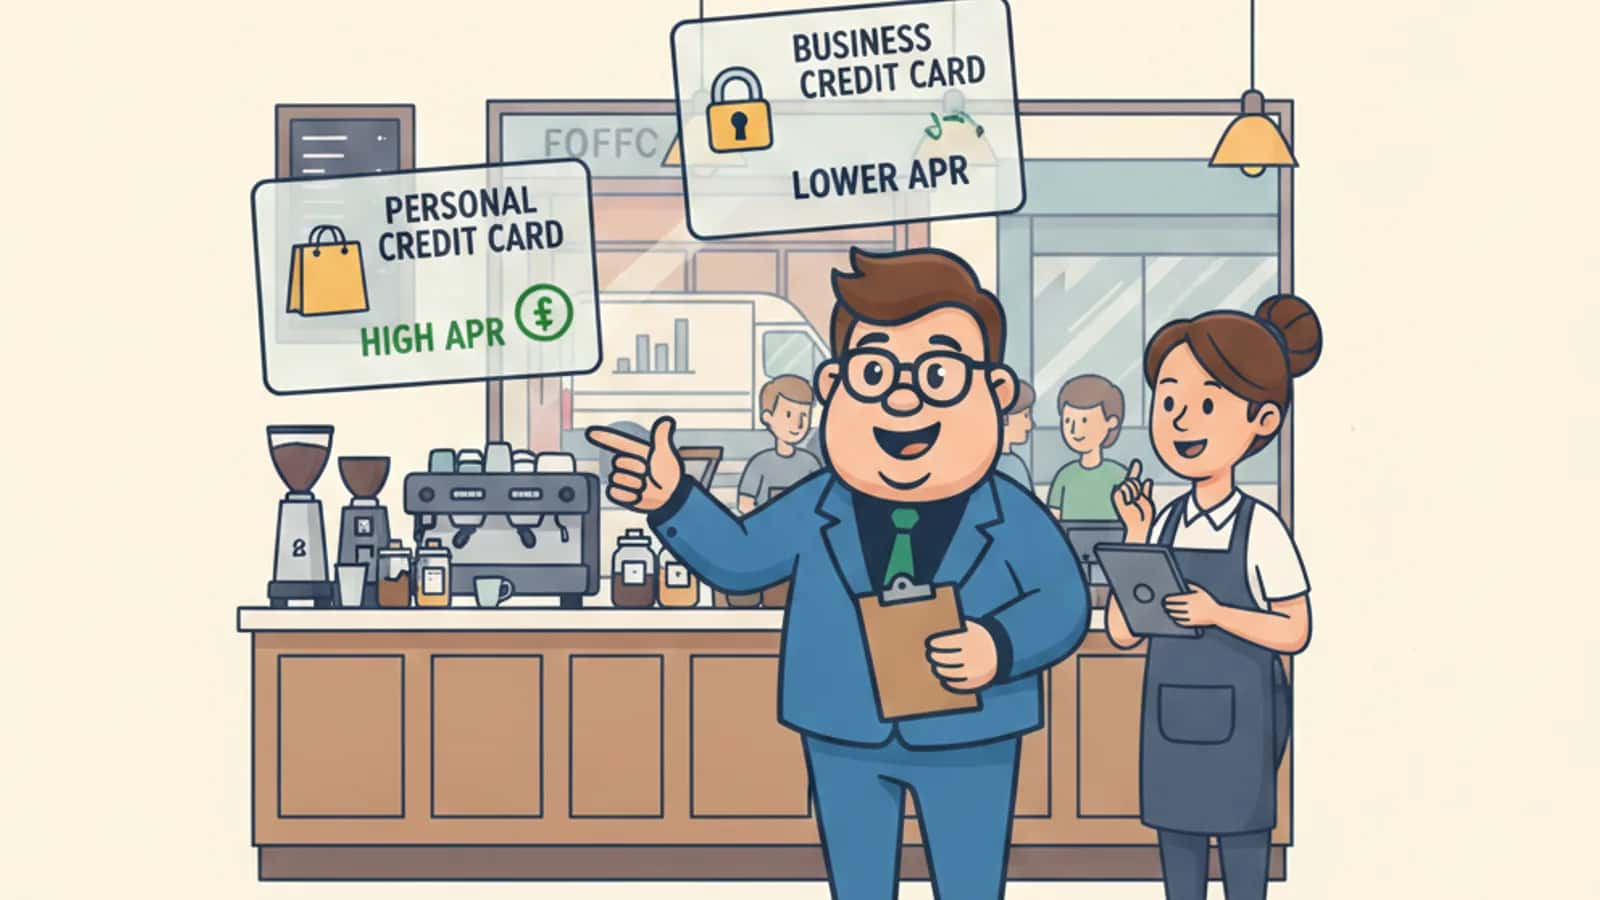
Business credit cards typically carry a higher representative APR than personal cards. Where a personal card might advertise a representative APR of 21-25%, business cards often sit in the 25-40% range, and some charge more. The key difference is that business cards are not regulated under the Consumer Credit Act in the same way personal cards are, which means lenders have more flexibility on pricing.
That said, APR is rarely the deciding factor for businesses that manage their card correctly. If you clear the full balance each month, the interest rate is irrelevant. What matters is whether the card gives you enough headroom to cover supplier payments, ad spend, or stock without touching your overdraft, and whether the fee structure makes commercial sense for your turnover.
When APR does matter
- You carry a balance month to month
- You use the card to fund longer-term purchases and repay over several months
- You're comparing a card with a 0% introductory period against one without
If you regularly carry a balance, a lower APR card with a modest annual fee will almost always beat a high-rewards card with a 35%+ rate. For more on how credit costs compare across funding types, see this guide on business overdraft vs line of credit vs loan.
How Do Annual Fees Affect Which Business Credit Card Is Best?
Annual fees on UK business credit cards range from £0 to several hundred pounds per year, and a higher fee does not automatically mean a worse deal. The question is whether the rewards, cashback, or features offset what you pay.
A card charging £150 per year but returning 1.5% cashback on all spend breaks even at £10,000 of annual card spend. Spend £30,000 a year on that card and you're £300 ahead after the fee. Spend £5,000 and you're behind.
How to assess whether an annual fee is worth it:
- Estimate your average monthly card spend across all categories
- Calculate the cashback or points value at the card's earn rate
- Subtract the annual fee
- Compare the net figure against a no-fee card's return on the same spend
Also factor in secondary benefits: travel insurance, airport lounge access, or free employee cards can add real value if your business uses them. If they don't match how you actually operate, ignore them in the calculation.
What Credit Limit Should You Look for in a Business Card?
The right credit limit depends on your monthly spend, payment cycles, and how you use the card. A limit that's too low creates friction, you hit the ceiling before the statement date, payments get declined, and you lose the float benefit. A limit that's too high isn't a problem in itself, but it does affect your business credit profile.
Most UK businesses operating on a standard 30-day payment cycle need a limit that comfortably covers their peak monthly spend, with headroom for unexpected costs. For an agency billing £50,000 a month in media spend, a £5,000 limit is useless. For a sole trader covering travel and software subscriptions, £5,000 might be plenty.
What affects the limit you're offered
- Business turnover and trading history
- Credit history of the business (and sometimes the director)
- Whether a personal guarantee is required
- The card provider's own risk appetite
Limits on business credit cards through Funding Fred's panel range from £1,000 to £250,000+. The 2-minute eligibility check gives you a realistic picture of what you're likely to be offered before any hard credit search is run.
How to Compare Rewards Programs Across Different Business Cards
Not all rewards programs are equal, and the headline earn rate rarely tells the full story. To genuinely compare rewards across business cards, you need to look at earn rate, redemption value, category bonuses, and expiry rules together.
Key questions to ask for each card
- What is the base earn rate (e.g. 1 point per £1 spent)?
- Are there bonus categories that match your spending (fuel, travel, advertising, office supplies)?
- What is each point actually worth when redeemed, and for what (cashback, travel, vouchers)?
- Do points expire, and is there a cap on how much you can earn?
- Can rewards be pooled across employee cards?
A card offering 3x points on advertising spend is extremely valuable for an e-commerce brand running paid social campaigns. That same card might be mediocre for a construction firm whose spend is mostly fuel and materials.
Common mistake: comparing earn rates without checking redemption values. A card earning 2 points per £1 where each point is worth 0.3p is worse than a card earning 1 point per £1 where each point is worth 1p.
What Hidden Fees Should You Watch Out for on Business Cards?
The headline APR and annual fee are the costs most businesses focus on. The fees that actually catch businesses out tend to be buried in the terms.
Fees to check before applying:
| Fee Type | What to Look For |
|---|---|
| Foreign transaction fee | Typically 2.5-3% on non-sterling purchases |
| Cash advance fee | Often 3-5% of the amount, plus immediate interest |
| Late payment fee | Fixed charge, often £12,£25, plus potential rate increase |
| Over-limit fee | Charged if spend exceeds your credit limit |
| Replacement card fee | Some providers charge for additional or replacement cards |
| Balance transfer fee | Relevant if moving existing debt to a new card |
| Paper statement fee | Small but avoidable |
Foreign transaction fees are particularly relevant for businesses buying from overseas suppliers or travelling internationally. A card charging 2.99% on foreign spend adds nearly £300 in fees on £10,000 of international purchases.
Cash advance fees are a trap. Using a business credit card to withdraw cash or fund a bank transfer is expensive, interest typically starts immediately with no grace period, and the fee stacks on top. If you need fast access to working capital, a cash flow business loan is usually a cleaner option.
Are Business Credit Card Rewards Worth the Annual Fee?
Yes, but only if your spend volume and category mix align with the card's reward structure. For many UK SMEs, a well-matched rewards card with a £100,£200 annual fee will return more value than a no-fee card with a lower earn rate.
The break-even point varies by card. As a rough guide, if your business spends £1,500 or more per month on the card, a mid-tier rewards card with an annual fee will usually outperform a no-fee alternative. Below that level, a no-fee card with a straightforward cashback rate is simpler and often better value.
One thing to watch: rewards cards tend to carry higher APRs. If there's any chance you'll carry a balance, the interest cost will wipe out the reward value quickly. Rewards cards work best when the balance is cleared in full each month. You can explore this further in what to know about business credit cards in the UK.
How Do Introductory APR Offers Work on Business Cards?
Some business credit cards offer a 0% introductory period on purchases, balance transfers, or both, typically lasting three to twelve months. During this period, no interest is charged on the qualifying balance.
These offers are useful for businesses with a specific upcoming spend: fitting out an office, buying equipment, or covering a seasonal stock build. You get the purchase power now and pay down the balance interest-free over the promotional period.
What to watch
- The 0% period has a hard end date. Any remaining balance reverts to the standard rate, often 30%+, on that date
- Minimum monthly payments are still required; missing one can cancel the introductory rate immediately
- Balance transfer offers often carry a transfer fee (typically 1-3% of the amount moved)
- Not all business card providers offer introductory rates; they're more common on personal cards
Introductory offers are not a substitute for working capital planning. If you can't realistically clear the balance before the rate reverts, factor the full APR into your cost calculation from the start.
Cash Back vs Points Rewards: Which Is Better for Your Business?
Cashback is simpler. Points can be worth more, but only if you actively use them.
Cashback: Returns a percentage of spend as cash, credited to your statement or account. Rates typically range from 0.5% to 2% depending on the card and category. No redemption decisions needed, no expiry risk, and the value is predictable. For most UK SMEs that want low admin, cashback is the better default.
Points: Earn at a rate per pound spent and redeem against travel, vouchers, or statement credit. The potential value per point is often higher than cashback, particularly for business travel redemptions, but you need to actively manage the account to get that value out.
Choose cashback if:
- You want simplicity and low admin
- Your spend is spread across many categories
- You don't travel frequently for business
Choose points if:
- You have high spend in specific categories (travel, advertising)
- You or your team travel regularly and can use airline or hotel points
- You have the time to manage a loyalty programme
For businesses running significant ad spend, some cards offer category-specific cashback on digital advertising that can return meaningful sums. An e-commerce brand spending £20,000 a month on paid search earning 1% cashback gets £2,400 back per year, before any annual fee offset.
Can You Negotiate Your Business Card's APR or Credit Limit?
On APR: it's possible, but less common with business cards than personal ones. Providers set rates based on risk assessment, and most won't move on the standard rate unless you have a strong relationship and a long track record. What you can sometimes negotiate is a fee waiver, an introductory offer, or a rate reduction if you've been offered a better deal elsewhere.
On credit limits: yes, and this is worth doing regularly. If your business has grown, your turnover has increased, or you've been managing the card well for 12+ months, a limit increase request is reasonable. Most providers have a formal review process; some will increase proactively if your spend pattern warrants it.
Practical steps:
- Check your current limit against your actual monthly spend, if you're regularly using more than 70% of the limit, request a review
- Prepare recent business bank statements and management accounts before calling
- Ask specifically about a limit increase rather than a full re-application, as the latter may trigger a new hard credit search
- If your current provider won't move, compare alternatives, a new card from a different provider may offer a higher limit from the start
If your business has outgrown what a high street bank will offer, it's worth looking at specialist providers. See how business credit score factors into limit decisions before you apply.
Which Business Credit Card Is Best for Your Spending Category?
The best card for your business depends on where most of your spend actually goes. There is no single best card, the right answer is category-specific.
Spend category matching:
| Spending Profile | What to Prioritise |
|---|---|
| High ad spend (Google, Meta) | Cards with digital advertising cashback or bonus points |
| Frequent business travel | Cards with airline miles, lounge access, no FX fees |
| Fuel and fleet | Cards with fuel cashback or fleet management features |
| Supplier payments | High limit, long interest-free period, fast approval |
| Staff expenses | Employee cards, spend controls, virtual cards |
| Mixed/general spend | Flat-rate cashback, no annual fee |
A common mistake is picking a card based on its highest-tier reward category when that category represents 10% of actual spend. Map your last three months of business spending by category, then match the card's bonus structure to where the bulk of your money actually goes.
What Happens If You Miss a Payment on a Business Card?
Missing a payment on a business credit card triggers several consequences, and they can compound quickly.
Immediate effects
- A late payment fee (typically £12,£25)
- Interest charged on the outstanding balance from the due date
- Potential loss of any introductory 0% rate
Longer-term effects
- A missed payment is reported to business credit reference agencies, which can affect future borrowing
- If the director provided a personal guarantee, a persistent default may affect their personal credit file too
- Some providers increase the standard interest rate after missed payments
If you know a payment will be late, contact the provider before the due date. Many will agree a short extension or payment plan without registering a formal default, particularly if you have a clean history. Waiting until after the missed date gives you fewer options.
For context on how business credit history affects future funding, see the guide on business credit score.
Do Business Credit Cards Affect Your Personal Credit Score?
This depends on the card, the provider, and whether a personal guarantee was given.
In most cases, a business credit card taken out in the company's name does not appear on the director's personal credit file, provided the account is managed well. However, there are two situations where it can:
- Personal guarantee: If you signed a personal guarantee as part of the application, defaults or serious delinquency on the business card can be reported against your personal credit profile
- Sole trader cards: Some providers treat sole trader business cards as personal credit products, meaning the account may appear on your personal credit file regardless
At the application stage, some providers run a hard search on the director's personal credit file as part of their underwriting process, even for a limited company card. Funding Fred's initial 2-minute check is separate from a card provider's full application, it involves no hard credit search and gives you a picture of likely eligibility before anything is recorded. Read business credit card eligibility in the UK: the key points for the key considerations.
If avoiding a personal guarantee is a priority, see the guide on no personal guarantee business loans for context on how guarantee requirements vary across products.
How Often Should You Compare and Switch Business Credit Cards?
Review your business credit card at least once a year, and definitely when any of the following happen: your limit hasn't kept pace with your spending, a promotional rate is about to expire, your business has grown significantly, or a competitor card is offering materially better terms.
The market moves. A card that was competitive two years ago may now have a higher fee, a lower earn rate, or a limit that no longer fits your needs. Switching isn't disruptive, most businesses can be set up with a new card within days through modern providers.
Signs it's time to compare
- You're regularly hitting your credit limit before the statement date
- Your cashback or rewards return is less than the annual fee
- You're paying foreign transaction fees on regular overseas purchases
- Your bank still hasn't raised a limit you requested 12 months ago
- Staff are putting company spend on personal cards because the business card limit is too low
Switching does involve a new credit application and potentially a hard search, so it's worth comparing properly before applying. A no-obligation eligibility check through Funding Fred takes two minutes and gives you a realistic view of what's available before committing. Business Credit Cards. Without the Fuss. For the wider context, read a closer look at the best business credit cards in the UK.
Next steps for how to compare business credit cards apr fees limits and rewards
Knowing how to compare business credit cards, APR, fees, limits and rewards, means looking at the full picture, not just the headline rate. For most UK businesses, the credit limit and approval speed matter more than a marginal difference in APR. The fee structure needs to stack up against your actual spend. And the rewards programme only adds value if it matches where your money actually goes.
The businesses that get the most from a business credit card are the ones that match the card to their spending profile, clear the balance monthly, and review the arrangement regularly. Staff putting company spend on personal cards, a limit that hasn't moved in years, and no visibility over who spent what, these are problems a better card can fix.
Run a 2-minute eligibility check with Funding Fred. No hard credit search. No obligation. See which leading card providers match your business before you commit to anything.
If you're also weighing up other funding options alongside a business credit card, the guide on alternative business funding options UK covers eight routes worth comparing.
Frequently asked questions
What Is the Difference Between Business and Personal Credit Card APR?
Business credit cards typically carry a higher representative APR than personal cards. Where a personal card might advertise a representative APR of 21-25%, business cards often sit in the 25-40% range, and some charge more. The key difference is that business cards are not regulated under the Consumer Credit Act in the same way personal cards are, which means lenders have more flexibility on pricing.
How Do Annual Fees Affect Which Business Credit Card Is Best?
Annual fees on UK business credit cards range from £0 to several hundred pounds per year, and a higher fee does not automatically mean a worse deal. The question is whether the rewards, cashback, or features offset what you pay.
What Credit Limit Should You Look for in a Business Card?
The right credit limit depends on your monthly spend, payment cycles, and how you use the card. A limit that's too low creates friction, you hit the ceiling before the statement date, payments get declined, and you lose the float benefit. A limit that's too high isn't a problem in itself, but it does affect your business credit profile.
How to Compare Rewards Programs Across Different Business Cards?
Not all rewards programs are equal, and the headline earn rate rarely tells the full story. To genuinely compare rewards across business cards, you need to look at earn rate, redemption value, category bonuses, and expiry rules together.
What Hidden Fees Should You Watch Out for on Business Cards?
The headline APR and annual fee are the costs most businesses focus on. The fees that actually catch businesses out tend to be buried in the terms.
Are Business Credit Card Rewards Worth the Annual Fee?
Yes, but only if your spend volume and category mix align with the card's reward structure. For many UK SMEs, a well-matched rewards card with a £100,£200 annual fee will return more value than a no-fee card with a lower earn rate.
Written by
The Funding Fred Editorial Team creates plain-English guides to help business owners understand funding options, eligibility, and application readiness before they compare finance options.
Reviewed by
UK business finance content reviewer
Robert reads our UK business finance guides before they go live, checking each one is accurate, easy to follow, and reflects how lending actually works today — not how a brochure says it should. He's listed on the FCA Register, approved as an SMF3 (AR) Executive Director at Switcha Limited, and connected to Lucky Growth Partners Ltd through its appointed representative relationship, so the regulated detail gets a properly qualified second read.