
Business Credit Card Guides
Business credit cards explained for UK businesses. Compare limits, interest, fees, and rewards before you apply for flexible everyday spending power.
Business credit cards explained
Use these guides to understand how business credit cards work, how limits and interest are set, and how to choose a card that fits your everyday spending.
What to compare before you apply
Credit limit
Limits are usually based on your trading history, turnover, and credit profile, and can range from a few hundred pounds to a much larger facility.
Interest and fees
Compare the representative APR, any annual fee, and how interest is charged if you carry a balance rather than clearing it in full each month.
Rewards and controls
Some cards offer cashback or rewards, and many let you issue employee cards with individual spending limits for better control.
Eligibility and trading history
Providers usually weigh time trading, turnover, and credit profile. Knowing yours up front avoids wasted applications.
Latest guides
Interest-Free Business Credit Cards vs Interest-Free Days: What Is the Difference?
Interest-free business credit cards offer a fixed promotional period (typically 3 to 12 months) during which no interest is charged on purchases or balance transfers. Interest-free days, by contrast, are the standard grace period built into most business credit cards, usually up to 56 days, that applies each billing cycle when you clear the full balance.
Business Credit Card Eligibility UK: Requirements and Checks Explained
To qualify for a business credit card in the UK, you typically need to be a registered UK business or self-employed individual, have a UK business bank account, and pass a credit assessment that looks at both your business and personal credit history.
VAT and Business Credit Card Expenses: Records, Receipts and Reclaiming VAT
You cannot reclaim VAT on business credit card expenses using a card statement alone. HMRC requires a valid VAT invoice or VAT receipt that meets specific content rules.
Are Business Credit Card Fees and Interest Tax-Deductible in the UK?
Yes, business credit card fees and interest charges are generally tax-deductible in the UK, provided the card is used wholly and exclusively for business purposes. Annual fees, transaction fees, and interest paid on business purchases can all be claimed as allowable business expenses.
Business Credit Card Minimum Payments, Late Fees and Missed Payments Explained
A minimum payment on a business credit card is the smallest amount you must pay each month to keep the account in good standing, typically a percentage of the balance or a fixed floor, whichever is higher. Miss it, and you'll face a late fee, a possible penalty interest rate, and damage to your business credit profile.
Representative APR vs Purchase Rate on a Business Credit Card: What UK Businesses Actually Need to Know
The representative APR on a business credit card is the headline annual cost figure that includes interest and any mandatory fees, shown as a single percentage. The purchase rate is just the interest rate applied to goods and services you buy on the card.
Why Was My Business Credit Card Application Declined? What to Do Next
A business credit card application gets declined because a provider found something in your business or personal credit profile, trading history, or application details that didn't meet their criteria.
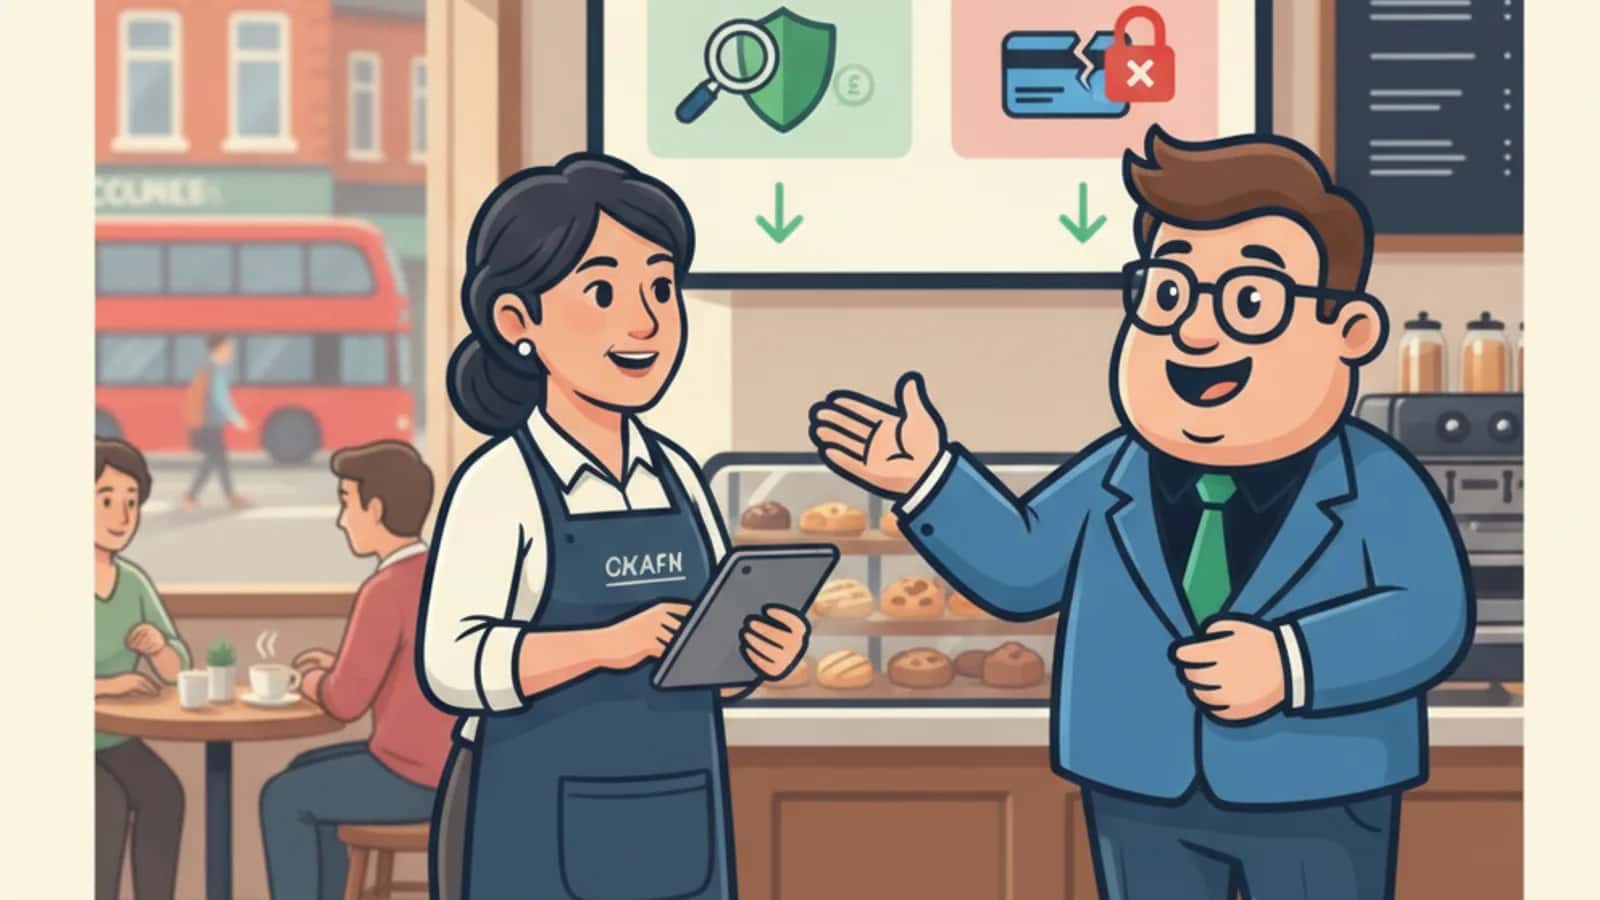
Soft Search vs Hard Search for a Business Credit Card Application
A soft search is a limited credit check that does not affect your business or personal credit score and is invisible to other lenders. A hard search is a full credit check triggered when you formally apply for a business credit card, it is visible to other lenders and can temporarily lower your score.
Does Applying for a Business Credit Card Affect Your Personal Credit Score?
Yes, applying for a business credit card can affect your personal credit score, but how much depends on the card provider, your business structure, and whether a personal guarantee is required. Most UK business card applications trigger a hard credit search on the director or sole trader, which leaves a temporary mark on your personal credit file.
Business Credit Cards questions
The important details before you check eligibility.
How is a business credit card different from a business loan?
A business credit card gives you a revolving limit for everyday spending, with interest only on what you use. A business loan is usually a fixed lump sum with scheduled repayments.
What credit limit can a business get?
Limits vary by provider and depend on turnover, trading history, and credit profile. Facilities commonly range from a few hundred pounds up to £250,000.
Will applying affect my credit score?
An initial eligibility check is often a soft search that does not affect your score. A full application may involve a hard credit check, so confirm with the provider before you proceed.
Can a limited company and a sole trader both apply?
Yes, though the application and any personal guarantee requirements can differ. Providers assess eligibility based on the business structure and trading history.
Ready when you are
Explore business credit card options
Answer a few questions to see what credit card limits could be available for your business. It only takes about 2 minutes, with no hard credit check to start.