Soft Search vs Hard Search for a Business Credit Card Application
A soft search is a limited credit check that does not affect your business or personal credit score and is invisible to other lenders. A hard search is a full credit check triggered when you formally apply for a business credit card, it is visible to other lenders and can temporarily lower your score.
Quick answer
A soft search is a limited credit check that does not affect your business or personal credit score and is invisible to other lenders. A hard search is a full credit check triggered when you formally apply for a business credit card, it is visible to other lenders and can temporarily lower your score. Understanding the difference between a soft search vs hard search for a business credit card application helps you protect your credit profile while shopping around for the right card.
Key takeaways
- A soft search lets lenders check your eligibility without leaving a mark visible to other lenders or affecting your credit score
- A hard search is recorded on your credit file when you submit a full business credit card application and stays visible for up to 24 months
- Multiple hard searches in a short period can signal financial stress to lenders and reduce your chances of approval
- Most eligibility checkers and pre-qualification tools, including Funding Fred's 2 min check, use a soft search only
- Funding Fred's initial eligibility check is separate from a card provider's full application, which will involve its own credit assessment
- You can check your business credit file without triggering a hard search by using your credit reference agency's own monitoring tools
- Hard searches cannot normally be removed from your credit file unless they were recorded in error
- Spacing out full applications and using soft search tools first is the most practical way to protect your credit profile
What Is the Difference Between a Soft Search and Hard Search for a Business Credit Card Application
A soft search gives a lender a partial view of your credit file, enough to indicate whether you are likely to qualify, without creating a footprint visible to other lenders. A hard search is a full credit check tied to a specific credit application and is recorded on your file for other lenders to see.
This distinction matters most when you are comparing business credit cards across multiple providers. If every comparison triggered a hard search, you could end up with five or six credit footprints before you had even chosen a card.
Soft search
- Used for eligibility checks, pre-qualification, and credit monitoring
- Visible only to you, not to other lenders
- Does not affect your credit score
- Typically used at the "comparing options" stage
Hard search
- Triggered when you submit a full application for a business credit card
- Recorded on your personal and/or business credit file
- Visible to other lenders for up to 24 months
- Can temporarily reduce your credit score by a small number of points
Most UK business credit card providers will run a hard search on the director's or owner's personal credit file when a full application is submitted, because small business card decisions are frequently based on the owner's personal creditworthiness.
Does a Soft Search Affect My Business Credit Score
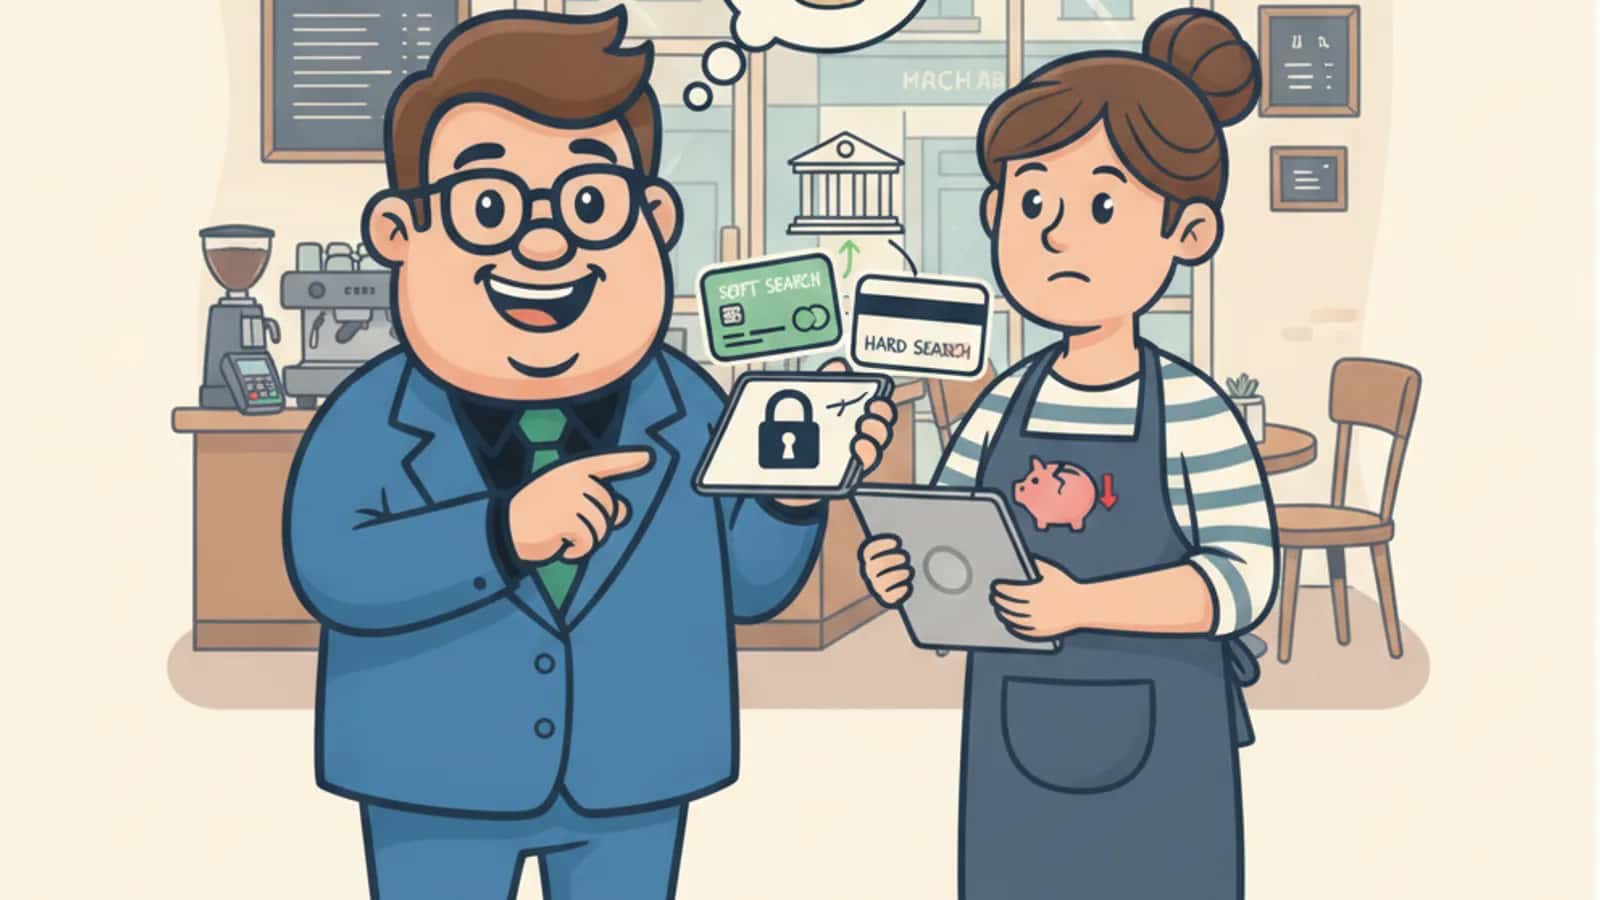
No. A soft search does not affect your business or personal credit score, and it is not visible to other lenders. It is recorded on your own credit file so you can see who has checked, but it carries no weight in any lender's credit decision. For more detail, see our guide to business credit cards and personal credit scores.
This is why soft searches are used for eligibility checks and pre-qualification tools. Lenders and comparison platforms can give you a realistic indication of approval likelihood without leaving any mark that could count against you.
One common mistake is assuming that any credit check is damaging. Checking your own credit file, through Experian, Equifax, or TransUnion, is always a soft search and will never hurt your score.
What Information Do Lenders See With a Soft Search vs Hard Search
A soft search gives a lender a summary view: enough to assess broad eligibility, but not the full picture used to make a lending decision. A hard search gives the lender access to your full credit history, including payment behaviour, existing credit balances, defaults, and any County Court Judgements (CCJs).
| What lenders can see | Soft search | Hard search |
|---|---|---|
| Basic identity and address | Yes | Yes |
| Existing credit accounts summary | Partial | Full |
| Payment history | Limited | Full |
| Defaults and CCJs | Sometimes | Yes |
| Current balances and utilisation | Limited | Full |
| Previous hard search footprints | No | Yes |
| Visible to other lenders | No | Yes |
For business credit card applications, the hard search typically covers the director's personal credit file and, depending on the provider, may also include a search of the business's own credit record at Companies House-linked credit reference data.
Will a Hard Search Hurt My Ability to Get Approved for Other Cards
A single hard search is unlikely to cause a significant problem. The concern arises when multiple hard searches appear in a short period, because other lenders can see them and may interpret the pattern as financial pressure or a high volume of credit-seeking behaviour.
Hard searches can temporarily reduce your personal credit score by a small number of points. The exact impact varies by credit reference agency and your existing credit profile, there is no single published figure that applies to every business owner.
When it matters most
- You are planning to apply for a business loan or mortgage in the near future
- You have a thin credit file with limited positive history to offset the inquiry
- You have already had two or more hard searches in the past three to six months
If you are in any of these situations, using soft search eligibility tools before committing to a full application is the sensible approach. See our guide to business credit scores for more on how lenders assess creditworthiness.
How Long Does a Hard Search Stay on My Business Credit Report
Hard searches typically remain on a personal credit file for 12 months in terms of scoring impact, and remain visible to lenders for up to 24 months. After 24 months, they drop off the file entirely.
For business credit files held by commercial credit reference agencies, the retention period may differ slightly by agency. Experian's guidance confirms that commercial hard inquiries are recorded when a business applies for credit and remain part of the business's credit history.
The practical takeaway: a hard search from a business credit card application made today will still be visible to lenders until mid-2028. That is worth bearing in mind if you are planning any significant financing in the next two years.
Can I Get a Business Credit Card With Just a Soft Search
No business credit card provider will issue a card based solely on a soft search. The soft search is used at the eligibility or pre-qualification stage only. Once you decide to proceed, the provider will run a full hard search as part of their credit assessment before making a final decision.
What you can do is use soft search tools to narrow down your options before triggering any hard searches. Funding Fred's eligibility check uses a soft search to match your business with business credit cards from leading card providers, with no hard check to start and no obligation. That initial check is entirely separate from a card provider's own full application process, which will include its own credit assessment and hard search.
This means you can run a 2 min check, see which providers are likely to consider your business, and then choose where to apply, rather than applying blind and collecting hard search footprints along the way.
Which Business Credit Cards Only Do Soft Searches, and How Many Hard Searches Is Too Many
No UK business credit card provider uses only a soft search for final approval, all providers that extend credit will run a hard search before issuing a card. The difference is at the pre-application stage: some providers and platforms offer soft search eligibility checks before you formally apply, and some do not.. For more detail, see our guide to business credit card eligibility in the UK.
How many hard searches is too many?
There is no fixed threshold, but two or more hard searches within a 30-day window can start to raise flags with some lenders. Three or more in 90 days on a thin credit file is likely to affect both your score and your approval odds at providers who run automated decisioning.
The practical rule: use soft search tools to identify your best-fit options, then apply to one or two providers rather than five. If the first application is declined, wait at least 60 to 90 days before applying elsewhere where possible. For more on what to do after a decline, the business loan declined guide covers the same principles.
Can I Check My Business Credit Without a Hard Search
Yes. Checking your own business credit file, through Experian Business, Equifax Business, or TransUnion, is always a soft search and will never affect your score or appear to other lenders.
You can also check your business's public filing information through Companies House at no cost. This does not constitute a credit check at all.
For a fuller picture of what lenders see, it is worth pulling a report from at least two of the main credit reference agencies, as not all lenders report to all three. Understanding your current position before you apply for a business credit card gives you a much clearer sense of which providers are realistic options.
What Happens If I Apply for Multiple Business Cards at Once
Each full application triggers a separate hard search. Applying for three business credit cards on the same day means three hard searches recorded on your file, all visible to lenders simultaneously.
Other lenders reviewing your file will see the volume of recent applications. Even if each individual search is small, the combined picture can suggest a business that is struggling to access credit, which can make providers more cautious, not less.
A better approach:
- Run a soft search eligibility check first (such as Funding Fred's no obligation 2 min check)
- Identify one or two providers that are a strong fit for your business
- Apply to your preferred option first
- If declined, wait 60 to 90 days before applying elsewhere
This approach also applies if you are considering a business overdraft vs line of credit vs loan alongside a card, multiple credit applications across different product types in a short window all leave hard search footprints.
How Long After a Hard Search Can I Apply for Another Business Card
There is no mandatory waiting period set by any regulator. The practical guidance from credit reference agencies is to allow at least 30 to 90 days between full credit applications where possible, to avoid a cluster of hard searches that could reduce your approval odds.
If your first application was declined, it is worth understanding why before applying again. A declined application does not itself appear on your credit file, but the hard search that accompanied it does. Applying again quickly without addressing the underlying issue tends to result in another decline and another hard search footprint.
For businesses with a limited credit history, building a stronger profile first, through a business credit score review, correcting any errors on file, and ensuring Companies House records are up to date, is more productive than rapid reapplication. For the wider context, read a closer look at business credit cards for bad credit.
Can I Remove a Hard Search From My Business Credit Report
Only if it was recorded in error. If a hard search appears on your file without your authorisation, for example, if a provider ran a full credit check when you only consented to a soft search, you can raise a dispute with the credit reference agency that holds the record.
If the search was legitimately triggered by an application you made, it cannot be removed. It will remain on your file for up to 24 months and then drop off automatically.
To raise a dispute, contact the relevant credit reference agency directly: Experian, Equifax, or TransUnion. Each has a statutory complaints process and must investigate within a set timeframe under UK data protection law.
Next steps for soft search vs hard search for a business credit card application
The soft search vs hard search distinction for a business credit card application is not just technical detail, it has a direct effect on your credit profile and your approval odds across multiple providers.
Soft searches cost you nothing and leave no mark. Use them. Run an eligibility check before you commit to any full application, and use the results to identify which providers are a realistic fit for your business's size, turnover, and credit history.
When you do apply, apply selectively. One well-matched application is far better than four speculative ones. Space out any additional applications if your first choice does not work out, and check your own credit file first so there are no surprises.
Funding Fred's eligibility check is a no hard check to start, no obligation way to see which business credit cards from leading card providers match your business, whether you need higher limits, employee cards, virtual cards, cashback on ad spend, or up to 56 days interest-free. The 2 min check gives you a clear picture before any hard search is involved. Business Credit Cards. Without the Fuss.
Frequently asked questions
What Is the Difference Between a Soft Search and Hard Search for a Business Credit Card Application?
A soft search gives a lender a partial view of your credit file, enough to indicate whether you are likely to qualify, without creating a footprint visible to other lenders. A hard search is a full credit check tied to a specific credit application and is recorded on your file for other lenders to see.
Does a Soft Search Affect My Business Credit Score?
No. A soft search does not affect your business or personal credit score, and it is not visible to other lenders. It is recorded on your own credit file so you can see who has checked, but it carries no weight in any lender's credit decision. For more detail, see our guide to business credit cards and personal credit scores.
What Information Do Lenders See With a Soft Search vs Hard Search?
A soft search gives a lender a summary view: enough to assess broad eligibility, but not the full picture used to make a lending decision. A hard search gives the lender access to your full credit history, including payment behaviour, existing credit balances, defaults, and any County Court Judgements (CCJs).
Will a Hard Search Hurt My Ability to Get Approved for Other Cards?
A single hard search is unlikely to cause a significant problem. The concern arises when multiple hard searches appear in a short period, because other lenders can see them and may interpret the pattern as financial pressure or a high volume of credit-seeking behaviour.
How Long Does a Hard Search Stay on My Business Credit Report?
Hard searches typically remain on a personal credit file for 12 months in terms of scoring impact, and remain visible to lenders for up to 24 months. After 24 months, they drop off the file entirely.
Can I Get a Business Credit Card With Just a Soft Search?
No business credit card provider will issue a card based solely on a soft search. The soft search is used at the eligibility or pre-qualification stage only. Once you decide to proceed, the provider will run a full hard search as part of their credit assessment before making a final decision.
Written by
The Funding Fred Editorial Team creates plain-English guides to help business owners understand funding options, eligibility, and application readiness before they compare finance options.
Reviewed by
UK business finance content reviewer
Robert reads our UK business finance guides before they go live, checking each one is accurate, easy to follow, and reflects how lending actually works today — not how a brochure says it should. He's listed on the FCA Register, approved as an SMF3 (AR) Executive Director at Switcha Limited, and connected to Lucky Growth Partners Ltd through its appointed representative relationship, so the regulated detail gets a properly qualified second read.
Sources
- Hard Credit Inquiries And Soft Credit Inquiries
- Searches And Credit Checks
- Hard Vs Soft Credit Checks What You Should Know
- Soft Pull Vs Hard Pull
- Hard Inquiry Vs Soft Inquiry
- Soft Vs Hard Credit Checks
- Hard Inquiry Vs Soft Inquiry
- Understanding Credit Checks Hard Searches And Soft Searches
- Whats The Difference Between Hard And Soft Credit Inquiries