Can You Withdraw Cash on a Business Credit Card? Fees and Interest Explained
Yes, you can withdraw cash on most business credit cards, but it is processed as a cash advance rather than a standard purchase. Cash advances on UK business credit cards typically carry a fee of 2-5% of the amount withdrawn, a higher interest rate than your purchase APR, and interest starts accruing immediately with no grace period.
Quick answer
Yes, you can withdraw cash on most business credit cards, but it is processed as a cash advance rather than a standard purchase. Cash advances on UK business credit cards typically carry a fee of 2-5% of the amount withdrawn, a higher interest rate than your purchase APR, and interest starts accruing immediately with no grace period. For most businesses, it is an expensive last resort.
Key takeaways
- Cash withdrawals on business credit cards are classed as cash advances, not purchases
- Expect a cash advance fee of 2-5% of the amount withdrawn, often with a minimum charge
- Interest on cash advances starts on the day of withdrawal, there is no interest-free period
- Cash advance APRs are usually higher than purchase APRs, often significantly so
- Your cash advance limit is typically 20-25% of your total credit limit
- Using a debit card or a dedicated business current account is almost always cheaper for cash
- Repeated cash advances can affect your business credit profile
- Checking eligibility for a Business Credit Card with higher limits and spend controls is a better route for most UK SMEs
What Is a Cash Advance on a Business Credit Card?
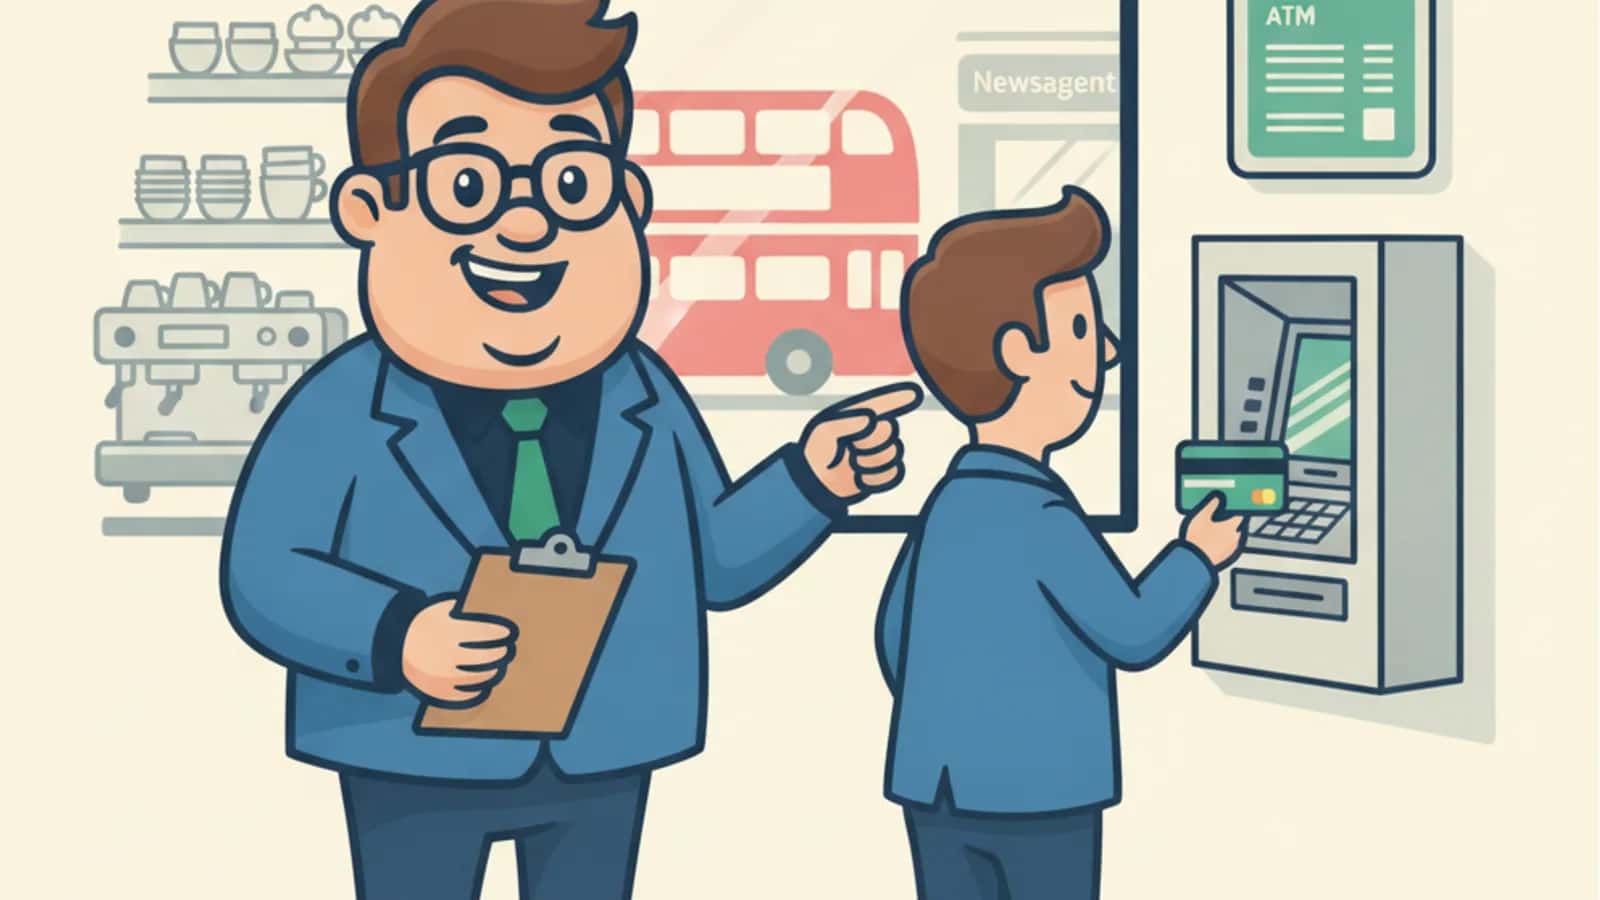
A cash advance is when you use your business credit card to withdraw physical cash, at an ATM, a bank counter, or sometimes via a convenience cheque issued by the card provider. The card network processes it differently from a purchase, and that difference costs you money.
Unlike a purchase, a cash advance does not benefit from any interest-free period. The moment the cash leaves the machine, interest starts running. Card providers treat cash advances as higher-risk transactions, so they apply a separate fee structure and a higher APR from day one.
Cash-equivalent transactions are also classed as cash advances on most UK business cards. These include:
- Buying foreign currency or traveller's cheques
- Loading prepaid cards
- Purchasing gift cards in bulk (varies by provider)
- Gambling transactions on some cards
How Much Does It Cost to Withdraw Cash from a Business Credit Card?
Cash advance fees on UK and international business credit cards are typically 2-5% of the amount withdrawn, with a minimum charge that varies by provider. On top of that fee, you pay interest at the cash advance APR from the date of withdrawal. For additional context, see a deeper look at comparing business credit cards.
For example, based on published card terms from US providers (which reflect the same fee structure seen on UK cards):
- Wells Fargo's Signify Business Cash card charges a cash advance fee of either $10 or 5% of the amount, whichever is greater
- SDCCU business credit card rates show a cash advance fee structure alongside a higher APR for cash transactions
- Climb Credit Union updated its business card cash advance limit terms effective 29 June 2026, signalling how actively providers manage this product feature
In the UK, the Business Credit Card Fees and APR Explained resource confirms that cash advance fees and higher APRs are standard across UK card providers.
Quick example: Withdraw £500 on a card with a 3% cash advance fee and a 30% cash advance APR. You pay £15 immediately in fees. If you clear the balance after 30 days, you also pay roughly £12.50 in interest. Total cost of accessing £500: approximately £27.50.
What Is the Difference Between Cash Advance Fees and Regular Purchase Fees?
Standard purchases on a business credit card carry no transaction fee and benefit from an interest-free period, typically up to 56 days if you pay in full each month. Cash advances have neither of those advantages.
| Feature | Standard Purchase | Cash Advance |
|---|---|---|
| Transaction fee | None | 2-5% (minimum charge applies) |
| Interest-free period | Up to 56 days | None, interest starts immediately |
| APR | Standard purchase rate | Higher cash advance rate |
| ATM access | No | Yes |
| Affects credit utilisation | Yes | Yes (separate cash limit) |
The gap between purchase APR and cash advance APR matters. Experian research shows average credit card interest rates in the US exceeding 20% APR, and UK cash advance rates often sit above purchase rates by several percentage points. Always check your specific card agreement.
Do Business Credit Cards Charge Interest on Cash Withdrawals, and When Does It Start?
Yes. Every mainstream UK business credit card charges interest on cash advances, and it starts on the day of the transaction. There is no grace period, no 30-day window, and no way to avoid it by paying early, though paying quickly does reduce the total interest you pay.
This is the single most important thing to understand about cash advances. A business owner who pays their card in full every month and assumes they have 56 days interest-free will be surprised. Cash advances sit outside that arrangement entirely.
The cash advance APR is also usually higher than the purchase APR. Some UK card providers set cash advance rates at 27-30% APR or above, even when the purchase rate is lower.
Are There Limits on How Much Cash You Can Withdraw?
Your cash advance limit is a sub-limit of your total credit line, not the full amount. Most card providers set this at 20-25% of the total credit limit.
So if your business card has a £10,000 limit, your cash advance limit might be £2,000,£2,500. Climb Credit Union's updated business card agreement, effective June 2026, specifically addresses how cash advance limits are structured and communicated to cardholders.
Providers set these sub-limits deliberately. They want to limit exposure to high-risk transactions. If cash access is a regular need for your business, a card with a low cash advance limit will not solve the problem, and the fees will compound quickly.
Can You Get a Cash Advance from Any ATM with a Business Credit Card?
Most business credit cards on the Visa or Mastercard networks can be used at any ATM that accepts those networks. That covers the vast majority of cash machines in the UK and internationally.
A few practical points:
- You need a PIN set on your business card, not all cards come with one by default, so check with your provider
- Some ATMs impose their own withdrawal fees on top of your card's cash advance fee
- International withdrawals add a foreign transaction fee on top of the cash advance fee
- Daily ATM withdrawal limits may apply, set by either your card provider or the ATM operator
The process is the same as using a debit card at a cash machine. Insert card, enter PIN, select amount. The difference is entirely in what it costs.
Can You Withdraw Cash from a Business Credit Card at a Bank Teller?
Yes, in most cases. You can request a cash advance over the counter at a bank branch that carries the same card network (Visa or Mastercard). You will need photo ID and your card, and the teller processes it as a cash advance transaction.
Some providers also issue convenience cheques, paper cheques drawn against your credit card account. These are treated as cash advances and carry the same fees and immediate interest. They are not the same as a standard business cheque.
Bank teller advances are less common now that ATMs are widely available, but they can be useful for larger amounts above ATM daily limits.
Which Business Credit Cards Let You Withdraw Cash Without Fees?
A small number of credit unions and specialist providers have eliminated or reduced cash advance fees. Sesloc Federal Credit Union, for example, removed cash advance fees on its credit cards entirely. This is unusual, most mainstream card providers maintain the fee structure.
In the UK, the picture is similar. Fee-free cash advances are rare on business credit cards from high street banks and mainstream providers. Some cards waive the fee for the first withdrawal or during an introductory period, but this is not standard.
The honest answer for UK businesses: If cash access without fees is a regular requirement, a business debit card linked to a current account is a more practical tool. A business credit card is better suited to managing supplier payments, controlling staff spend, earning cashback on ad spend and stock purchases, and accessing up to 56 days interest-free on purchases, not for routine cash withdrawals.
Does Withdrawing Cash on a Business Credit Card Hurt Your Credit Score?
Cash advances themselves do not appear as a separate negative entry on your business credit file. But the knock-on effects can affect your business credit score in two ways.
First, cash advances increase your credit utilisation. If your total limit is £10,000 and you draw £2,000 in cash, your utilisation rises. High utilisation is a negative signal to lenders.
Second, if the cash advance fees and interest push your balance up and you miss a payment or carry a high balance for several months, that payment behaviour is reported and affects your profile.
For businesses planning to apply for higher limits or additional finance, keeping utilisation low and balances manageable matters. See also how business credit score affects your access to credit more broadly.
Is It Better to Use a Debit Card or Credit Card for Cash Withdrawals?
For cash withdrawals specifically, a business debit card is almost always cheaper. There are no cash advance fees, no separate higher APR, and no immediate interest accrual. You are drawing from funds already in your account.
The trade-off is that a debit card offers no credit headroom. If the cash need exceeds your current account balance, a debit card will not help.
A business credit card is better for:
- Spreading supplier payments over up to 56 days interest-free
- Earning cashback on purchases
- Giving employees cards with spend controls
- Keeping working capital in the account longer
A debit card is better for:
- Routine cash withdrawals
- Situations where you want no interest risk
If your business regularly needs cash and your current account balance is too low to support it, that is a cash flow issue worth addressing at the root. Options include a business overdraft or line of credit or cash flow business loans rather than repeated cash advances on a credit card.
What Is the Cheapest Way to Get Cash as a Business Owner?
The cheapest options, in rough order of cost:
- Business current account debit card, no fees, no interest, uses existing funds
- Business overdraft, interest only on what you use, arranged in advance
- Business line of credit, flexible drawdown, lower rates than cash advances
- Invoice finance, release cash tied up in unpaid invoices, see invoice financing costs
- Business credit card cash advance, highest cost option, use only when no alternative exists
The cash advance route makes sense only in a genuine short-term emergency with no other access. Even then, clearing the balance as fast as possible limits the interest damage.
What Happens If You Cannot Pay Back a Business Credit Card Cash Advance?
If you cannot repay the cash advance balance, interest compounds daily at the cash advance APR. Because there is no grace period, the balance grows from day one.
Missing minimum payments triggers late payment fees on top of the interest. Sustained non-payment leads to default, which is reported to credit reference agencies and damages your business credit profile. This makes future borrowing, including higher card limits, business loans, or invoice finance, harder to access. For more detail, see our guide to business credit card minimum payments.
For businesses already stretched, a business debt consolidation loan or a restructured facility may be worth exploring before the situation escalates.
If a business credit card cash advance was used to cover a payroll or supplier shortfall, that is a signal the business needs a more structured working capital facility rather than a revolving credit product used for cash.
Next steps
Cash advances on business credit cards are possible, but they are expensive by design. The fee hits immediately, the interest starts the same day, and the APR is higher than your purchase rate. For UK businesses, the answer to "can you withdraw cash on a business credit card? fees and interest explained" is: yes, but almost always at a cost that outweighs the convenience. Compare this with the practical guide to business credit card APR.
The better move for most SMEs is to treat the business credit card as a purchasing and cash flow tool, covering supplier invoices, ad spend, and team expenses within the interest-free window, and to keep cash access separate through a business current account or a structured facility.
If the real problem is a credit limit that hasn't moved in years, a bank that takes weeks to respond, or staff putting company spend on personal cards, those are the friction points worth fixing. A 2-minute eligibility check with no hard credit search is a good place to start.
Check Eligibility Now, no obligation, no hard check to start. Leading card providers, limits from £1k to £250k+, virtual cards, employee cards, cashback, and up to 56 days interest-free. Business Credit Cards. Without the Fuss.
Frequently asked questions
What Is a Cash Advance on a Business Credit Card?
A cash advance is when you use your business credit card to withdraw physical cash, at an ATM, a bank counter, or sometimes via a convenience cheque issued by the card provider. The card network processes it differently from a purchase, and that difference costs you money.
How Much Does It Cost to Withdraw Cash from a Business Credit Card?
Cash advance fees on UK and international business credit cards are typically 2-5% of the amount withdrawn, with a minimum charge that varies by provider. On top of that fee, you pay interest at the cash advance APR from the date of withdrawal. For additional context, see a deeper look at comparing business credit cards.
What Is the Difference Between Cash Advance Fees and Regular Purchase Fees?
Standard purchases on a business credit card carry no transaction fee and benefit from an interest-free period, typically up to 56 days if you pay in full each month. Cash advances have neither of those advantages.
Do Business Credit Cards Charge Interest on Cash Withdrawals, and When Does It Start?
Yes. Every mainstream UK business credit card charges interest on cash advances, and it starts on the day of the transaction. There is no grace period, no 30-day window, and no way to avoid it by paying early, though paying quickly does reduce the total interest you pay.
Are There Limits on How Much Cash You Can Withdraw?
Your cash advance limit is a sub-limit of your total credit line, not the full amount. Most card providers set this at 20-25% of the total credit limit.
Can You Get a Cash Advance from Any ATM with a Business Credit Card?
Most business credit cards on the Visa or Mastercard networks can be used at any ATM that accepts those networks. That covers the vast majority of cash machines in the UK and internationally.
Written by
The Funding Fred Editorial Team creates plain-English guides to help business owners understand funding options, eligibility, and application readiness before they compare finance options.
Reviewed by
UK business finance content reviewer
Robert reads our UK business finance guides before they go live, checking each one is accurate, easy to follow, and reflects how lending actually works today — not how a brochure says it should. He's listed on the FCA Register, approved as an SMF3 (AR) Executive Director at Switcha Limited, and connected to Lucky Growth Partners Ltd through its appointed representative relationship, so the regulated detail gets a properly qualified second read.
Sources
- Sesloc Eliminates Cash Advance Fees On Credit Cards
- Signify Business Cash Credit Card Terms Conditions
- Business Credit Card Rates
- Cash Advance Limit Change Summary Business Cc Agreement Effective 6 29 2026
- Business Credit Card Fees Apr Explained
- Business Credit Card Cash Advance Fee Payroll Liquidity
- Current Credit Card Interest Rate