
Business Finance Guides
Plain-English guides to UK business loans, asset finance, invoice financing, and business credit cards. Compare lenders, check what you'll qualify for, and walk into a funding decision already knowing the answers.
Business Loans
View all
No Personal Guarantee Business Loans: Fast Funding Without Risking Personal Assets
Banks demand personal guarantees on 59% of small business loans, putting your house and savings at risk. No personal guarantee business loans protect your personal assets while providing the capital your business needs.
Personal Guarantees on Business Loans: What UK Business Owners Need to Know in 2026
A personal guarantee on a business loan makes you personally liable for the debt if your company defaults. Most traditional banks require unlimited personal guarantees, putting your home, savings, and personal assets at risk.
Asset Finance
View all
Personal Guarantees on Asset Finance: When Directors Are Asked to Sign
Directors are commonly asked to sign personal guarantees on asset finance deals to reduce lender risk, especially for newer companies or those with limited credit history. This makes directors personally liable for company debts if the business defaults, potentially putting personal assets including homes at risk.
Plant and Machinery Finance for UK Construction Businesses: Fast Funding Options for 2026
Plant and machinery finance for UK construction businesses provides funding from £1k to £5m for excavators, cranes, concrete mixers, and other essential equipment through hire purchase, finance lease, or contract hire arrangements.
Printing and Packaging Equipment Finance UK: Funding Presses and Production Lines
Printing and packaging equipment finance in the UK provides businesses with immediate access to production machinery through hire purchase, finance lease, or asset-backed lending from £1,000 to £5 million.
Bridging Loans
View all
Mixed-Use Property Bridging Finance: Shops, Flats and Semi-Commercial Assets
Mixed-use property bridging finance provides short-term funding from £25k to £25m+ for properties combining residential and commercial elements, such as shops with flats above.
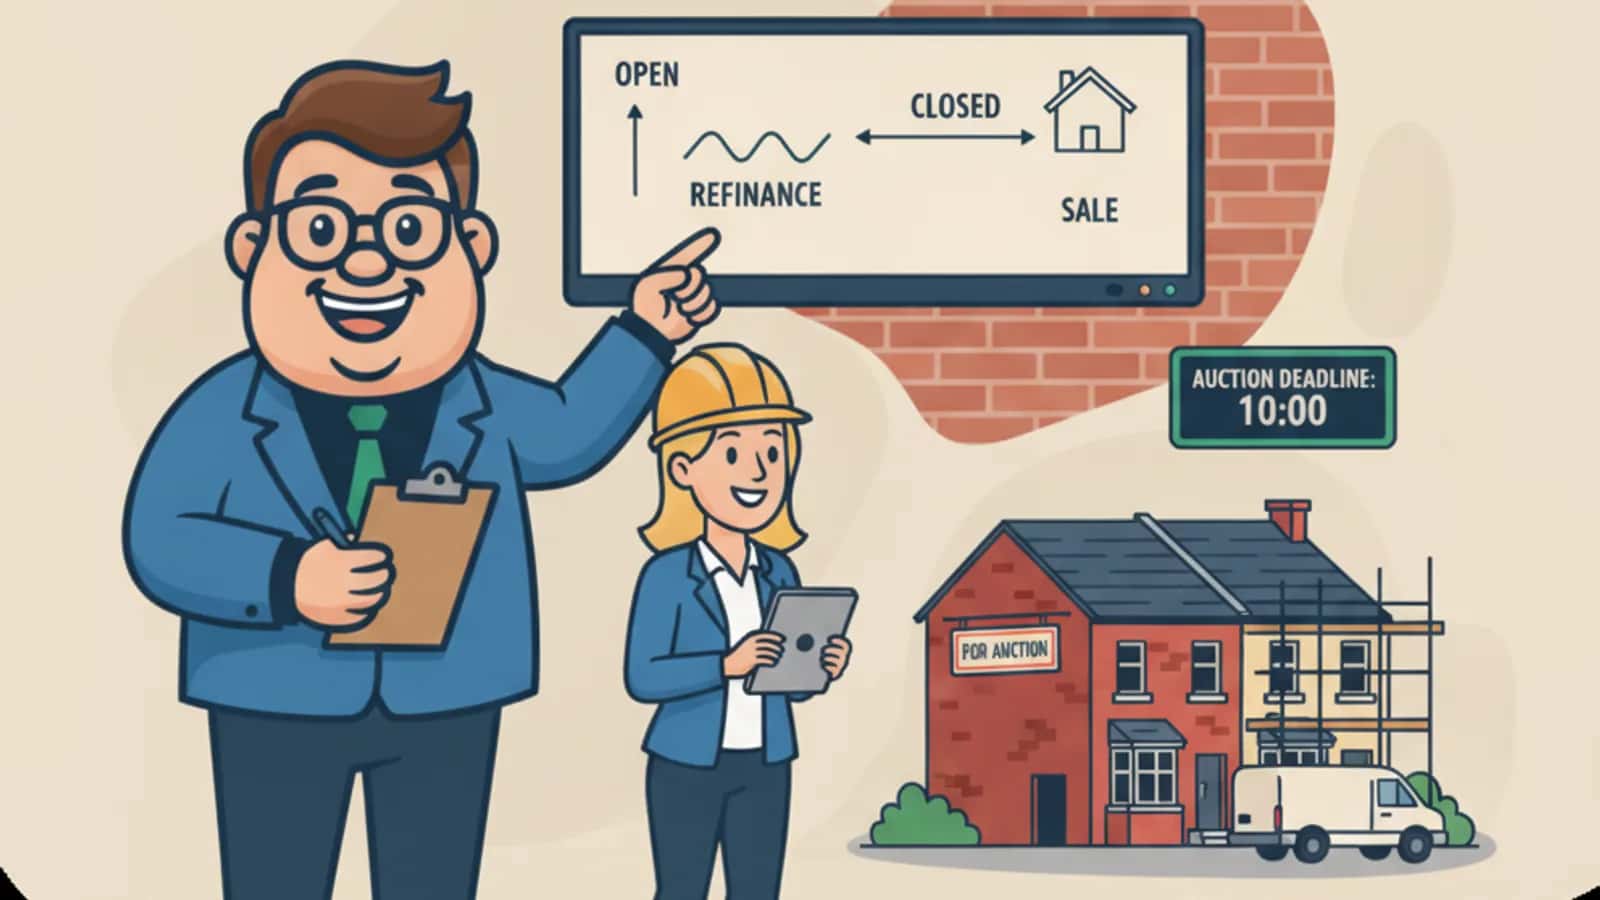
Open vs Closed Bridging Loans: Exit Strategy Guide for UK Property Investors
Open bridging loans don't require a fixed exit date or confirmed sale, while closed bridging loans have a predetermined repayment date with an agreed exit strategy already in place.
Development Finance
View all
Mezzanine Finance and JV Equity: UK Development Funding Compared
UK property developers seeking funding beyond traditional senior debt face two primary options: mezzanine finance provides structured secondary loans up to 90% of project costs, while JV equity partnerships can deliver 100% funding in exchange for profit sharing and reduced developer control.
Office-to-Residential Conversion Finance: Funding Change-of-Use Projects
Office-to-residential conversion finance: funding change-of-use projects requires specialist development finance rather than traditional mortgages. Most conversions use construction loans covering 60-70% of project costs at SOFR plus 350-550 basis points, with 18-36 month terms and 30-40% equity requirements.
Ready when you are
See what funding your business could get
Start a short eligibility check and compare selected business funding options. It only takes about 2 minutes, with no hard credit check to start.